Most markets are closed today due to Hurricane Sandy as it approaches the Northeast coast of the United States. Equity futures closed down, despite a ramp-up from deep losses that lasted until about 7 am MST. So far, the S&P 500 has maintained support around the 1400 level.
Monday, October 29, 2012
Impact of QE on Bonds
Via Zero Hedge (intro) and Societe Generale:
The Fed sees the need to reduce interest rates as it takes over the
US Treasury and MBS markets; but the ECB's actions are more aimed at
reducing divergences between peripheral nations and the core. As SocGen
notes, it remains unclear how and when the Fed would exit this situation and in Europe, bond market volatility remains notably elevated relative to the US and Japan as policy action absent a political, fiscal, and banking union remains considerably less potent.
Via SocGen:
Fed action pushes rates to record lows
The Fed bought around $2tn of securities since November 2008, pushing
rates to historical lows (US treasuries becoming popular safe havens
also contributed to lowering rates).

It remains unclear how and when the Fed would exit this situation.
Operation Twist expires at year-end and any extension seems to be put on
hold until after the presidential elections.
A potential Romney victory could bring an end to low QE rates in 2014 (when Mr Bernanke’s term expires).
As a result of the very low rate environment, the US equity risk premium is currently extremely high (6.3% in October 2012).
Hurdles in transmission of ECB monetary policy

Yield spreads divergence between peripheral countries and the rest of
the eurozone illustrates the difficulties the ECB faces in performing
its policy in the absence of a political, fiscal and banking union.
Since end-2011, unconventional measures from the ECB have had a
significant impact on rates. The launch of OMT could see peripheral
rates tighten even further.
However, bond market volatility in the euro area remains high
compared to the US and Japan even though it has decreased recently.

Provided that Mr. Rajoy requests a bailout as expected, rate
normalisation should continue, especially after Germany’s election in
September 2013.

Source: SocGen

Impact of QE on Equities
From Zero Hedge and Societe Generale:
Fed 'credibility' has boosted stocks from the start of its actions;
the ECB, however, only since OMT. But as SocGen's cross-asset class
research group notes, poor performance of the S&P 500 since QE3
announcement (-1.6%) may
well be an initial sign of a loss of impact from the Fed’s policy, and US equity volatility is rising - catching up to Europe's.
Via SocGen:
S&P 500 and QEs: third time lucky?

During the two phases of QE carried out by the Fed, US stocks
appreciated by around 48% at their peaks, on an annualised basis. The
rally during Operation Twist was milder, but still strong at +36%
(annualised). As a result, the S&P 500 gained about 15% (ann.) in
the past four years as the Fed resorted to unconventional policy tools.
Security purchases of past QEs have contributed to lowering rates, which
is bullish for risky assets like equities. The upcoming purchases of
QE3 aim to push stocks even higher. But, as current equity margins are
at historical high and in light of the global economic slowdown, can US
stock prices continue to climb at the same pace going forward? The poor
performance of the S&P 500 since QE3 announcement (-1.6%) may well
be an initial sign of a loss of impact from the Fed’s policy.
ECB: increased credibility but politics prevail

Mr Draghi took over as head of the ECB just one year ago, and already
the perception of the ECB’s monetary policy has changed radically. The
new president has adopted a more “Fed-like” policy: first with the
launch of 3-year LTROs in December 2011 to support bank liquidity; and,
more recently, with the OMT, the unlimited bond buying programme to
support sovereigns. Following Mr Draghi’s pledge to do “whatever it
takes” to save the euro and the subsequent announcement of the OMT, the
Euro Stoxx 50 rebounded (+15% in 10 weeks).

The ECB has removed some equity tail risk by providing European
governments with more time to find solutions to the euro crisis.
However, as Spain still has to request bailout help, the implementation
of ECB measures remains constrained by political decisions.

Source: SocGen
Sunday, October 28, 2012


Saturday, October 27, 2012
Defense sequestration targets small business
Washington lawmakers have failed to reach a compromise over how to
reduce the national debt, and the automatic budget cuts of the 2011
Budget Control Act are set to take force on January 2, 2013. These
automatic cuts, known as sequestration, are inflexible, across-the-board
cuts that were designed to be so harmful that no politician would ever
let them occur. Unfortunately, the White House and Congress have yet to
reach a deal that would prevent their implementation.
Sequestration is particularly harmful for national defense, as it
would cut another half trillion from the military's budget on top of
nearly $900 billion in cuts already under the Obama administration.
Contrary to public perception, most defense dollars today go to small
and medium-sized businesses rather than large firms. In a recent letter
to Ohio's congressional delegation, concerned small businesses wrote,
"[b]etween two-thirds and three-quarters of defense industrial purchases
go to smaller suppliers, and three-quarters of all defense related
manufacturing jobs are at supply chain firms." This means the real harm
of sequestration will fall disproportionately on small business owners
and entrepreneurs.
Defense Shouldn't Be the Target
"Sequestration will bring steep reductions to the defense budget at a time when the American military urgently needs to modernize the force and address longstanding maintenance and readiness shortfalls."Sequestration will bring steep reductions to the defense budget at a time when the American military urgently needs to modernize the force and address longstanding maintenance and readiness shortfalls.
Americans are rightfully concerned about the national debt, and many see the defense budget as a deserving target to cut. After all, popular perceptions of the Pentagon are still largely colored by Dwight Eisenhower's speech about the "military-industrial complex." Yet despite this common characterization, what America spends on its military is a relatively small (and shrinking) part of total government spending. When President Eisenhower warned of the military-industrial complex in 1961, the military accounted for 44 percent of the federal budget, well over 8 percent of GDP. Today, America devotes 15 percent of the federal budget to defense, just over 3.5 percent of its economy. Under current budget plans, defense spending will become the lowest national priority sometime in this decade after the Big Three entitlements, non-defense discretionary spending, and interest on the debt.
While about half of the defense budget is spent on people, the rest funds readiness, operations, training, research and development, and the purchase of goods and services for the three million people working for the Department of Defense. America's arsenal of democracy helps equip and serve those in uniform and plays a critical role in the American economy as both an employer and exporter. The aerospace and defense industry is the nation's largest net exporter, adding $89.6 billion in exports in 2010 and contributes 2.3 percent to the nation's economy.
A Reliance on Small Business
Small businesses are the lifeblood of the American economy. According to the Small Business Administration, 99.7 percent of all employer firms are small businesses. Small businesses have created 60 to 80 percent of net new jobs since 1990, and account for half of the nation's private sector workforce and economy. Moreover, small businesses produce 13 times more patents per employee than large firms. Since 1995, these smaller companies have hired 43 percent of all high-tech workers and are responsible for roughly one-third of all exports.Small businesses are just as vital to equipping and servicing the U.S. military as they are to the national economy. America's shipbuilding, aerospace, and defense manufacturing workforce employs more than one million people directly, many of whom are employed by small firms. Two-thirds to three-quarters of all defense industrial purchases are directed to small and medium-sized suppliers and vendors. As Aerospace Industries Association President Marion Blakey has put it, 70 cents of every defense dollar goes to small firms. In 2011, 20 percent of Department of Defense contracts and 35 percent of subcontracts were awarded to small businesses specifically.
"As Aerospace Industries Association President Marion Blakey has put it, 70 cents of every defense dollar goes to small firms." Small business' value to the defense industry goes beyond the raw percentages. Smaller, specialized firms are often the only producers of niche equipment, software or technology, and as such, play an indispensable role in the military's supply chain. Michael Petters, CEO of Huntington Ingalls, shipbuilder for the U.S. Navy and Coast Guard, notes that 60 percent of the firms that supply his shipyards are "sole source"—companies that may be the only possible provider for critical components. If sequestration breaks these lines, his whole supply chain could crumble. This could leave the U.S. Navy unable to find another business that can make the same parts for the ships built by Ingalls.
One firm of six employees produces a unique "Hot Press" furnace used in the manufacture of ceramic body armor plates that protect American soldiers, for example. If the demand for such furnaces goes down further, that firm could go out of business. If the Department of Defense wanted to resume furnace manufacture down the line, it would take approximately 18 to 24 months to restart production. In the meantime, there would be a gap in protection for U.S. fighting forces overseas.
Sequestration Will Hurt Small Firms Most
Several studies have already examined how sequestration will wreak havoc upon America's small businesses. Dr. George Fuller of George Mason University recently testified to the House Small Business Committee that in 2013 alone, sequestration will put at risk 2.14 million jobs, including over 950,000 small business jobs. In fact, 45 percent of job losses from the first year of sequestration will come from businesses with 500 or fewer employees.As one representative example, security and aerospace company Lockheed Martin has around 40,000 supplier contracts—12,000 of which come from small and minority-owned businesses. While Lockheed is arguably large enough to absorb substantial cuts, its second and third-tier suppliers and long-lead vendors are not as fortunate. If sequestration causes the Pentagon to break contracts with Lockheed, Lockheed will turn around and break contracts with its suppliers—in many cases, small and medium-sized firms. For these firms, sequestration may wipe out much of their expected operating profits and force them into contract termination suits whose costs are shifted up to the government from Lockheed instead of building products for the military. These lawsuits may end up costing the government almost as much as the sequestration cuts were designed to save in the first place.
The "fiscal cliff" and the uncertainties surrounding sequestration's resolution are coming at a time when America's small businesses are already feeling squeezed and worried about the future. Many of these smaller firms rely heavily on obtaining loans for future capital investment. Yet, according to a recent survey, 43 percent of small companies claimed that they needed extra funding but were unable to obtain loans over the past four years.
These trends are magnified by the cloud of uncertainty created by Washington. According to the National Small Business Association, 68 percent of small businesses said that economic uncertainty was the most significant challenge to their future growth and survival. Moreover, 34 percent of small business owners anticipate a recession in the coming year—the highest level since December 2009. The climate for small businesses is so acidic that only 25 percent of small business owners anticipate increasing their number of employees in the coming year, which is 15 percent fewer than in December 2011.
These impacts are not just limited to the future. The shadow of uncertainty has led to a soft sequestration already underway. At the Procurement Technical Assistance Center (PTAC) in Genesee County, Michigan, orders have already declined by 30 percent since their peak levels in 2010 due to ongoing defense cutbacks. These cuts are not simply "trimming the fat." Real businesses and smart owners that have succeeded in the past are falling victim to politics, which has allowed this threat to fester. Miller-Holzwarth, a 2007 recipient of the Small Businesses Association subcontractor of the year award, is going out of business due to the pervasive uncertainty surrounding defense budgets. This firm provided steady jobs in Salem, Ohio, for over 35 years yet it was powerless against the last three years of defense budget cuts and a future of much the same.
Lame Ducks Must Think Big
Unless Congress acts swiftly and decisively upon its return after the November elections, countless companies will follow in the footsteps of Miller-Holzwarth. The pillaging of America's small and medium aerospace and defense firms is not an exercise in responsible fiscal restraint but an arbitrary and inefficient process that will have lasting consequences for America's national security and the economy.In many ways, small businesses represent the very best of America. They represent the promise of a better life—the dream that can pay off with hard work, perseverance, and a touch of faith. Yet small businesses can only thrive in an environment that encourages, or at least does not inhibit, innovation and risk taking. Sequestration will hinder innovation by striking small and entrepreneurial businesses hardest.
Sean O'Keefe, chairman of the North American division of EADS, an aerospace and defense corporation, recently told Congress that "American workers are unemployed today because of the uncertainty that has been allowed to surround sequestration." The president can convene Congressional leaders at any time, however, and remove the threat of the fiscal cliff. But the clock is ticking and businesses are not waiting on Washington. They are already starting to act on their own.
The components of a deal are already in place. Both sides of the political aisle know they will need to give a little in order to avert sequestration. The issue is whether one side is willing to careen off the fiscal cliff rather than blink first. If Congress and the president address these major challenges confronting the American economy, then, as Australian Foreign Minister Bob Carr said recently in Washington, America is just "one budget deal away from banishing the notion of American declinism."
As politicians prepare to come up with a plan to strengthen the American economy, they would be wise to think first of those running and employed at America's small businesses. As EADS' O'Keefe also said, "the most vulnerable of these aerospace and defense suppliers are the vast number of small to mid-cap businesses that sustain millions of jobs, drive technology, and create the innovation that is the hallmark of American aerospace. While larger companies have the capacity to more successfully weather the impending fiscal storm, small businesses do not."
Mackenzie Eaglen is a resident fellow in the Marilyn Ware Center for Security Studies.
The Cantillon Effect Destroys Civilizations
Popular Delusions
Memo to Central Banks: You’re debasing more than our currency
By Dylan Grice, Societe Generale
At its most fundamental level, economic activity is no more
than an exchange between strangers. It depends, therefore, on a degree
of trust between strangers. Since money is the agent of exchange, it is
the agent of trust. Debasing money therefore debases trust. History is
replete with Great Disorders in which social cohesion has been
undermined by currency debasements. The multi-decade credit inflation
can now be seen to have had similarly corrosive effects. Yet central
banks continue down the same route. The writing is on the wall. Further
debasement of money will cause further debasement of society. I fear a Great Disorder.
I am more worried than I have ever been about the clouds
gathering today (which may be the most wonderful contrary indicator you
could hope for...). I hope they pass without breaking, but I fear the
defining feature of coming decades will be a Great Disorder of the sort
which has defined past epochs and scarred whole generations.
“Next to language, money is the most important medium through which modern societies communicate” writes Bernd Widdig in his masterful analysis of Germany’s inflation crisis “Culture and Inflation in Weimar Germany.”
His may be an abstract observation, but it has the commendable merit of
being true … all economic activity requires the cooperation of
strangers and therefore, a degree of trust between cooperating
strangers. Since money is the agent of such mutual trust, debasing money
implies debasing the trust upon which social cohesion rests.
So I keep wondering to myself, do our money-printing central banks and their cheerleaders understand the full
consequences of the monetary debasement they continue to engineer?
Inflation of the CPI might be a consequence both seen and measurable. A
broad inflation of asset prices might be a consequence seen, though not
measurable. But what about the consequences that are unseen but
unmeasurable – and are all the more destructive for it? I feel queasy
about the enthusiasm with which our wise economists play games with
something about which we have such a poor understanding.
If you take a look around you, any artefact you see will only
be there thanks to the cooperative behaviour of lots of people you don’t
know. You will probably never know them, nor they you. The screen you
watch on your terminal, the content you read, the orders which make the
prices flicker … the coffee you drink, the cup you hold, the bin you
throw it in afterwards … all your clothes, all your accessories, all
the buildings you’ve been in, all the cars … you get the idea. Without exception
everything you own, everything you want to own, everything you need,
and everything you think you need embodies the different skills and
talents of a mind-boggling number of complete strangers. In a very real
sense we constantly trust in strangers to a degree, as strangers trust
us. Such cooperative activity is to everyone’s great benefit and I find
it is a marvellous thing to behold.
The value strangers put on each other’s contributions manifests
itself in prices, and prices require money. So it is through money that
we express the extent of our appreciation for the many different
talents embedded in each thing we consume, and through money that our
skills are in turn valued by others. Money, in other words, is the agent
of this anonymous exchange, and therefore money is also the agent of
the hidden trust on which it depends. Thus, as Bernd Widdig reflects in
his book (which I urge you all to read), money …
“… is more than simply a tool for economic exchange; its
different qualities shape the way modern people think, how they make
sense of their reality, how they communicate, and ultimately how they
find their place and identity in a modern environment.”
Debasing money might be expected to have effects beyond the
merely financial domain. Of course, there are many ways to debase money.
Coin can be clipped, paper money can be printed, credit can be created
on the basis of demand deposits which aren’t there ... the effects are
ultimately the same though: the implied trust that money communicates
through society is eroded.To see how, consider the example of money printing by authorities. We know that such an exercise raises revenues since the authorities now have a very real increase in purchasing power. But we also know that revenue cannot be raised by one party without another party paying. So who pays?
If the authorities raise taxes explicitly and openly, voters know exactly why they have less spending power. They also know how much less spending power they have. But if the authorities instead raise money by simply printing it, they raise the revenue by stealth. No one knows upon whom the burden falls. People notice only that they can’t afford the things they used to be able to afford, or they can’t afford the things which everyone else can afford. They know that something is wrong, but they just don’t know what, why, or who is to blame. So inevitably they look for someone to blame.
The dynamic is similar to that found in the well-worn plot line in which a group of strangers are initially brought together in happier circumstances, such as a cruise, a long train journey or a weekend away. In the beginning, spirits are high. The strangers exchange jokes and get to know one another as the journey begins. Then some crime is committed. They know it must be one of them, but they don’t know who. A great suspicion ensues. All trust between them is broken down and the infighting begins....
So it is with monetary debasement, as Keynes understood deeply (so deeply, in fact, that it’s ironic so many of today’s crude Keynesians support QE so enthusiastically). In 1921 he said:
“By a continuing process of inflation, Governments can confiscate, secretly and unobserved, an important part of the wealth of their citizens. By this method they not only confiscate, but they confiscate arbitrarily;
and, while the process impoverishes many, it actually enriches some ….
Those to whom the system brings windfalls …. become “profiteers” who are
the object of the hatred … the process of wealth-getting degenerates
into a gamble and a lottery .. Lenin was certainly right. There is no
subtler, no surer means of overturning the existing basis of society
than to debauch the currency. The process engages all the hidden forces of economic law on the side of destruction, and does it in a manner which not one man in a million is able to diagnose.”
History is replete with Great Disorders in which currency
debasement has coincided with social infighting and scapegoating. I have
written in the past about the Roman inflation of the Third Century AD.
The following chart shows the rapid turnover of emperors during what is
known as the Third Century Crisis. As trade declined, crops failed and
the military suffered what must have seemed like constant defeat, it
wasn’t difficult for a successful or even popular general to convince
the rest of the empire that he’d make a better fist of governing.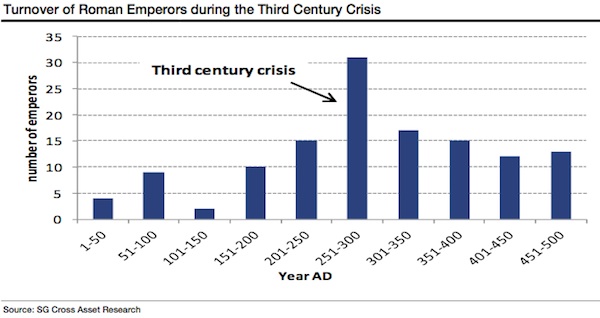
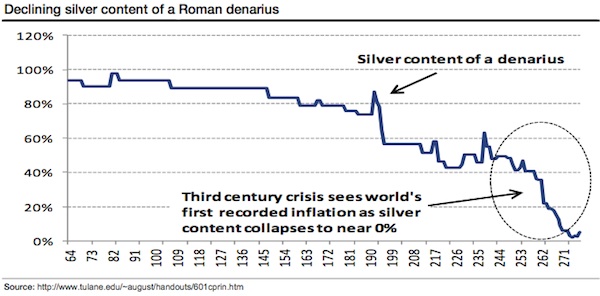
But this political turnover was accompanied by what may be history’s first recorded instance of systematic currency debasement. With the empire no longer expanding and barbarians being forced westwards by the migrations of the Steppe peoples, Rome’s borders were under threat. But the money required to fund defence wasn’t there. Successive emperors therefore reached the same conclusions that kings, princes, tyrants and democratically elected governments would later reach down the ages when faced with a perceived “shortage of money”: they created more by debasing the existing stock. In the second half of the third century, the silver content of a denarius had shrunk to zero. Copper coins disappeared altogether.
This debasement of currency also coincided with a debasement of society. Factions grew more suspicious of one another. Communities fragmented. And one part of the community bore the brunt of the fears: Christians. While Rome had always welcomed new religions and Gods, incorporating new foreign deities as their empire grew, Christians were altogether different. They rejected Rome’s gods. They refused to pray to them. They said that only their God was deserving of worship. The rest of the Romans concluded that this obstinacy must be a source of great anger for their own ancient Roman gods, and supposed that those gods must now be exacting their own great punishment in return.
So the Romans turned on their Christians with a great violence which lasted throughout the period of the currency debasement but peaked with Diocletian’s edict of 303 AD. The edict decreed, among other things, that Christian meeting places be destroyed, Christians holding office be stripped of that office, Christian freedmen be made slaves once more and all scriptures be destroyed. Diocletian’s earlier edict, of 301 AD, sought to regulate prices and set out punishments for ‘profiteers’ whose prices deviated from those set out in the edict.
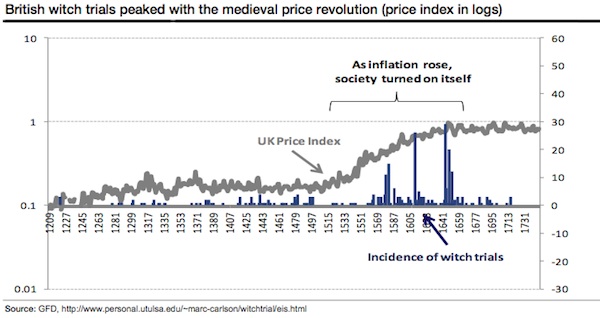
A similar dynamic seems evident during Europe’s medieval inflations, only now, the confused and vain effort to make sense of the enveloping turmoil saw the blame focus on suspected witches. The following chart shows the UK price index over the period with the incidence of witchcraft trials. Note the peak in trials coinciding with the peak of the price revolution.
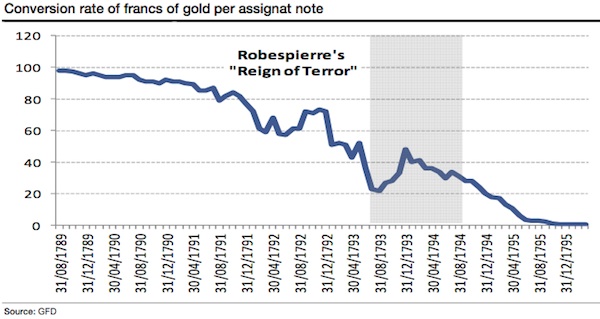
Were the same dynamics at work during the French Revolution of 1789? The narrative of Madame Guillotine and her bloody role is well known. However, the execution of royalty by the Paris Commune didn’t begin until 1792, and the Reign of Terror in which Robespierre’s Orwellian sounding “Committee of Public Safety” slaughtered 17,000 nobles and counter-revolutionaries didn’t start until well into 1793. In the words of guillotined revolutionary Georges Danton, this is when the French revolution “ate itself”. But the coincidence of these events to the monetary debasement is striking.
The political violence was justified in part by blaming nobles and counter-revolutionaries for galloping inflation in food prices. It saw ‘speculators’ banned from trading gold, and prices for firewood, coal and grain became subject to strict controls. According to Andrew Dickson White, author of “Fiat Money Inflation in France”, (echoing Keynes’ remark that “wealth-getting degenerates into a gamble and a lottery”) “economic calculation gave way to feverish speculation across the country.”
However, the most tragic of all the inflations in my opinion, and certainly the starkest example of a society turning on itself was the German hyperinflation. Its causes are well known. Morally and financially bankrupt by the First World War, the reparation demands of the Allies (which Keynes argued vociferously against) followed by the French occupation of the Ruhr served to humiliate a once-mighty nation, already on its knees.
And it really was on its knees. Germany simply had no way to pay. The revolution following the flight of the Kaiser was incomplete. Concern was widespread that Germany would follow the path blazed by Moscow’s Bolsheviks only a year earlier. A de facto civil war was being fought on the streets of major cities between extremist mobs of the left and right. Six million veterans newly demobilized, demoralized, dazed and without work were unable to support their families ... the great political need was to pay off the “internal debts” of pensions, life insurance and welfare support in any way possible. The risk of printing whatever was required was well understood. Bernhard Dernberg, vice chancellor in 1919, found himself overwhelmed with promises to pay for the war disabled, food subsidies, unemployment insurance, etc., but everyone knew where the money was coming from:
“A decision of the National Assembly is made. On its basis,
Reich Treasury bills are printed and on the basis of the Reich Treasury
bills, notes are printed. That is our money. The result is that we have
a pure assignat economy.”
But print they did. Prices would rise by a factor of one
trillion. At the end of the war, Germany owed 154bn Reichmarks to its
creditors. By November 1923, that sum measured in 1914 purchasing power
was worth only 15 pfennigs.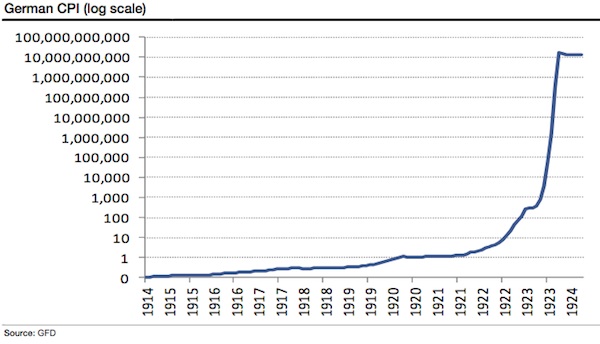
It is difficult to comprehend the psychological trauma inflicted by this episode. Inflation inverted the efficacy of correct behaviour. It turned the ethics of thrift, frugality and notions such as working hard today to bring benefit tomorrow completely on their heads. Why work today when your rewards would mean nothing tomorrow? What use thrift and saving? Why not just borrow in depreciating currency? Those who had worked and saved all their lives, done everything correctly and invested what they had been told was safe, were mercilessly punished for their trust in established principles, and their inability to see the danger coming. Those with no such faith who had seen the danger coming had benefited handsomely.
Everything, in other words, was dependent on one’s ability to speculate, recalling what Dickson White observed of the French Revolution and Keynes reflections more generally. Erich Remarque is best known for his anti-war novel “All Quiet on the Western Front” but perhaps his best work was the “The Black Obelisk” set in the early Weimar period, and a penetrating meditation on the upside-down world of inflation. The protagonist Georg poignantly captures this speculative imperative when he sits down and lets out a long sigh:
“Thank God that it’s Sunday tomorrow … there are no rates
of exchange for the dollar. Inflation stops for one day of the week.
That was surely not God’s intention when he created Sunday.”
Perhaps the most eloquent chronicler of the Weimar
hyperinflation was Elias Canetti, whose mother moved him from the
security of Zurich to Frankfurt in 1921 to take advantage of cheaper
living. Canetti never forgave her, and his life’s work shows what a
lasting impression the move from heaven to hell made:
“A man who has been accustomed to rely on (the monetary
value of the mark) cannot help feeling its degradation as his own. He
has identified himself with it for too long, and his confidence in it
has been like his confidence in himself … Whatever he is or was, like
the million he always wanted, he becomes nothing”
More tragic still was what German society became during the
inflation. Like other Axis countries on the wrong side of the War and
now in the grip of hyperinflation, Germany turned viciously on its Jews.
It blamed them for the surrounding evil as Romans had blamed
Christians, medieval Europeans had suspected witches, and French
revolutionaries had blamed the nobility during previous inflations. In
his classic “Crowds and Power”, Canetti attributed the horror of
National Socialism directly to a “morbid re-enaction impulse”.
“No one ever forgets a sudden depreciation of himself, for
it is too painful … The natural tendency afterwards is to find something
which is worth even less than oneself, which one can despise as one was
despised oneself. It is not enough to take over an old contempt and to
maintain it at the same level. What is wanted is a dynamic process of
humiliation Something must be treated in such a way that it becomes
worth less and less, as the unit of money did during the inflation. And
this process must be continued until its object is reduced to a state of
utter worthlessness. … In its treatment of the Jews, National Socialism
repeated the process of inflation with great precision. First they were
attacked as wicked and dangerous., as enemies; then, there not being
enough in Germany itself, those in the conquered territories were
gathered in; and finally they were treated literally as vermin, to be
destroyed with impunity by the million.
All this is very disturbing stuff, but testament to a
relationship between currency devaluation and social devaluation. Mine
is not a complete or in any way rigorous analysis, I know. I emphasize that it’s not in any way meant as some sort of crude mapping on to today’s environment.
My point is to show that money operates in many social domains beyond
the financial, and that tying currency devaluation to social devaluation
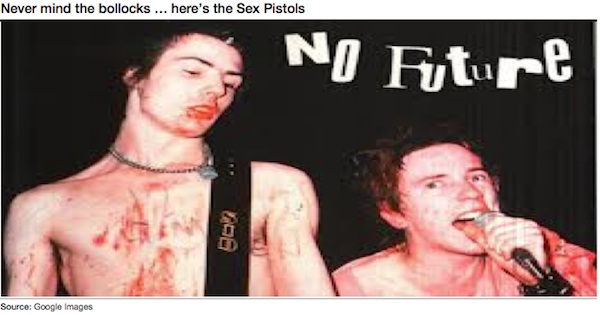
might have some merit.Consider some recent and less extreme currency inflations. The 1970s bear market in equities saw relatively mild inflation which was also characterized by relatively mild but nevertheless real factionalization of society. An ideological left vs right battle played out between labour and capital, unions and non-unions and perhaps most bizarrely, between rock and disco. As already stated, money implies a trust in the future. It implies that today’s money can be used in the future. So in the era of punk, did the Sex Pistols provide the most concise commentary of the malaise?
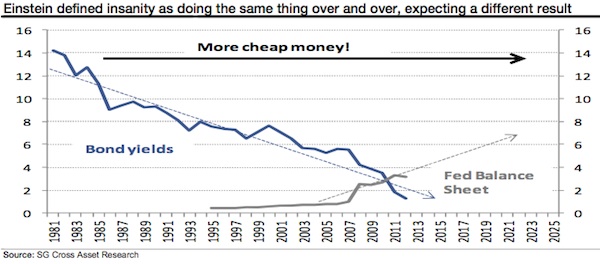
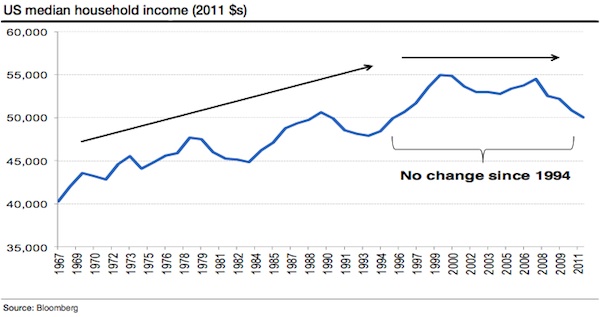
Which brings us to today. Despite the CPI inflation of the 1970s receding, our central banks have continued to play games with money. We’ve since lived through what might be the largest credit inflation in financial history, a credit hyperinflation. Where has it left us? Median US household incomes have been stagnant for the best part of twenty years (chart below)
Yet inequality has surged. While a record number of Americans are on food stamps, the top 1% of income earners are taking a larger share of total income than since the peak of the 1920s credit inflation. Moreover, the growth in that share has coincided almost exactly with the more recent credit inflation.
These phenomena are inflation’s hallmarks. In the Keynes quote above, he alludes to the “artificial and iniquitous redistribution of wealth” inflation imposes on society without being specific. What actually happens is that artificially created money redistributes wealth towards those closest to it, to the detriment of those furthest away.
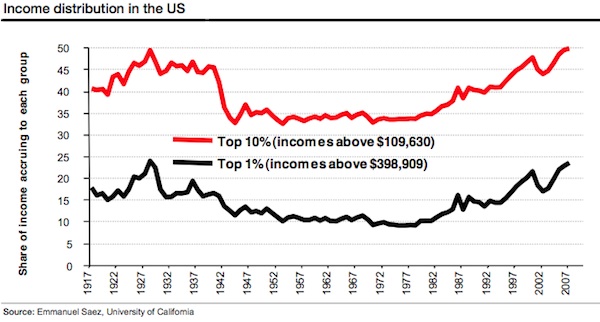
Richard Cantillon (writing decades before Adam Smith) was the first to observe this effect (hence “Cantillon effect”). He showed how those closest to the money source benefited unfairly at the expense of others, by thinking through the effects in Spain and Portugal of the influx of gold from the new world as follows:
“If the increase of actual money comes from mines of gold
or silver … the owner of these mines, the adventurers, the smelters,
refiners, and all the other workers will increase their expenditures in
proportion to their gains. . . . All this increase of expenditures in
meat, wine, wool, etc. diminishes of necessity the share of the other
inhabitants of the state who do not participate at first in the wealth
of the mines in question. The altercations of the market, or the demand
for meat, wine, wool, etc. being more intense than usual, will not fail
to raise their prices … Those then who will suffer from this dearness …
will be first of all the landowners, during the term of their leases,
then their domestic servants and all the workmen or fixed wage-earners
... All these must diminish their expenditure in proportion to the new
consumption …
(Quoted in Mark Thornton, “Cantillon on the Cause of the Business Cycle” Quarterly Journal of Austrian Economics Vol 9, No 3 [Fall 2006])
In other words, the beneficiaries of newly created money spend
that money and bid up the price of goods with their higher demand. Those
who suffer are those who have to pay newly higher prices but did not
benefit from the newly created money.The credit inflation analog to the Cantillon effect has played out perfectly in recent decades. Central banks provided cheap money to banks, the cheap money artificially inflated asset prices, artificially inflated asset prices made anyone connected to those assets rich as we became a nation of speculators, those riches were achieved at everyone else’s expense, and ‘everyone else’ has now realized what has happened and is understandable enraged … as Keynes explained, “Those to whom the system brings windfalls …. are the object of the hatred.
And now the social debasement is clear for all to see. The 99% blame the 1%, the 1% blame the 47%, the private sector blames the public sector, the public sector returns the sentiment … the young blame the old, everyone blame the rich … yet few question the ideas behind government or central banks ...

I’d feel a whole lot better if central banks stopped playing games with money. But I can’t see that happening anytime soon. The ECB has thrown the towel in, following the SNB last year in committing effectively to print unlimited amounts of money for the greater good. The BoE and the Fed have long since made a virtue of what was once considered a necessity, with what was once the unconventional conventional. As James Bullard told everyone a few weeks before the last Fed meeting, lest there be any doubt:
"Markets have this idea that, there's QE1 and QE2, so QE3
must be the same as those previous ones. It's not that clear to me that
this is the way this is going … it would just be to do balance sheet
policy as the exact analogue of interest rate policy."
In other words, the central banks’ balance sheets are the new
policy tool. As interest rates embarked on a multi-year decline from the
1980s on, central bank balance sheets are set to embark on a multi-year
climb ...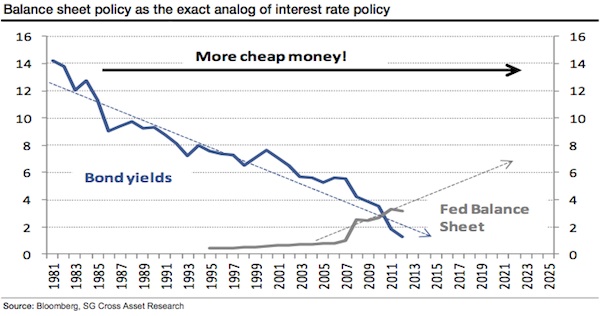
So as Nobel Prize winning experts in economics punch the air because inflation expectations have been rising since the policy was announced, “It’s the whole point of the exercise” (Duh!) the BoE admits that QE has mainly benefited the rich, but vows to continue anyway.
All I see is more of the same - more money debasement, more unintended consequences and more social disorder. Since I worry that it will be Great Disorder, I remain very bullish on safe havens. The next few issues of Popular Delusions will outline some thoughts on what exactly that means.
What Is the Cantillon Effect?
by John Aziz of Azizonomics
Expansionary monetary policy constitutes a transfer of purchasing
power away from those who hold old money to whoever gets new money. This
is known as the Cantillon Effect, after 18th Century economist Richard
Cantillon who first proposed it. In the immediate term, as more dollars
are created, each one translates to a smaller slice of all goods and
services produced.
How we measure this phenomenon and its size depends how we define money. This is illustrated below.
Here’s GDP expressed in terms of the monetary base:

Here’s GDP expressed in terms of M2:

And here’s GDP expressed in terms of total debt:

What is clear is that the dramatic expansion of the monetary base
that we saw after 2008 is merely catching up with the more gradual
growth of debt that took place in the 90s and 00s.
While it is my hunch
that overblown credit bubbles are better liquidated than reflated (not
least because the reflation of a corrupt and dysfunctional financial
sector entails huge moral hazard), it is true the Fed’s efforts to
inflate the money supply have so far prevented a default cascade. We should expect that such initiatives will continue, not least because Bernanke has a deep intellectual investment in reflationism.
This focus on reflationary money supply expansion was fully expected
by those familiar with Ben Bernanke’s academic record. What I find more
surprising, though, is the Fed’s focus on banks and financial
institutions rather than the wider population.
It’s not just the banks that are struggling to deleverage. The
overwhelming majority of nongovernment debt is held by households and
nonfinancials:

The nonfinancial sectors need debt relief much, much more than the
financial sector. Yet the Fed shoots off new money solely into the
financial system, to Wall Street and the TBTF banks. It is the financial
institutions that have gained the most from these transfers of
purchasing power, building up huge hoards of excess reserves:

There is a way to counteract the Cantillon Effect, and expand the
money supply without transferring purchasing power to the financial
sector (or any other sector). This is to directly distribute the new
money uniformly to individuals for the purpose of debt relief; those
with debt have to use the new money to pay it down (thus reducing the
debt load), those without debt are free to invest it or spend it as they
like.
Friday, October 26, 2012
Wake Up "Quick" to Fiscal Storm
By Becky Quick, contributor
FORTUNE
-- It's bad enough that we can't have a serious conversation about any
of our nation's problems during the election season. Now folks like Paul
Krugman are trying to ensure that we can't have one after the election
either.The New York Times columnist and Nobel Prize-winning economist recently wrote a column attacking a bipartisan proposal to reduce the nation's debt problems, arguing, "We're not facing any kind of a fiscal crisis." He maintains that President Barack Obama, if reelected, should reject calls to resurrect the debt-reduction blueprint.
The only problem with Krugman's critique? It is hard to find anyone who actually agrees with him. He's certainly not getting assent from Alan Simpson and Erskine Bowles, who headed the panel that crafted the ideas Krugman is now attacking. Nor will the economist find much support from the 44 CEOs of Fortune 500 companies who are now advocating the plan. And most notably, perhaps, he's not charming former President Bill Clinton, for whom Bowles served as chief of staff. Clinton's office provided me with the following statement when I called for comment. It's a damning retort to Krugman -- and a bold statement about a plan the Obama administration has failed to embrace, even though the President commissioned it:
"While everyone can find things to disagree with in the recommendations of the Simpson-Bowles commission, I believe it got some big things right: The debt will become a much bigger problem when normal economic growth returns and causes interest rates to rise; passing a credible 10-year plan now will keep the government's borrowing costs much lower than they will be without one; it's important not to impose austerity now before a growth trend is clearly established, because as the austerity policies in the eurozone and the U.S. show, that will slow the economy, cut jobs, and increase deficits; and any credible deficit-reduction plan requires three things -- spending reductions, revenue increases, and economic growth."
Let me add a few numbers to give context to Clinton's comments. America took in $2.45 trillion last year and spent $3.54 trillion, leaving us with a deficit of about $1.1 trillion. A nation with as much goodwill as ours can do that from time to time, but this marks the fourth year in a row we've spent over $1 trillion more than we took in. Just in that time, we've borrowed more than $17,000 for each man, woman, and child in the country.
The interest payments on all that debt are a potential tsunami of their own. We're spending $258 billion a year on interest payments for our massive debt. That's more than we spend on the departments of Commerce, Education, Interior, Energy, State, Homeland Security, and Justice combined. And the Congressional Budget Office projects that if we don't tackle some of this debt, our interest payments will soar to $1 trillion a year just over a decade from now.
As for our entitlements, the situation is equally dire. As the law is currently written, the Social Security trust fund will run dry in 2033. If nothing changes before then, Social Security recipients will have their benefits cut by 25%. Simpson-Bowles tries to keep the program solvent by putting in modest steps to raise the retirement age gradually far into the future -- by one year in 2050 and another in 2075 -- so as not to change the social promises made to people who are nearing retirement age now. But the longer we wait to discuss the real problems in entitlement programs and enact changes like this, the more draconian the fix will need to be.
That's why Krugman's claim that there is no fiscal crisis isn't just laughable, it's downright dangerous. Krugman throws down the gauntlet when he calls Simpson-Bowles "a really bad plan." As President Clinton notes, nearly every constituency will find some part of it hard to swallow. But the beauty of the plan is that it attempts to unify the country through shared sacrifice that is also grounded in some form of fiscal reality. And there's nothing "really bad" about that.
This story is from the November 12, 2012 issue of Fortune.
Thursday, October 25, 2012
Now That's One Bad Apple!
Apple reported their earnings after the market close, and it was a shocking disappointment! Stock futures dropped sharply.

Eurozone Downturn Deepens
from Mish Shedlock's blog:

1) UK's GDP went positive.
2) Durable goods orders rose. Unfortunately, it was due to aircraft, not consumer goods.

Wednesday, October 24, 2012
Calculation for GDP
GDP = C + I + G + Net Exports, or GDP is equal to Consumption (Consumer and Business) + Investment + Government Spending + Net Exports (Exports – Imports). This is true for all times and countries.


Tuesday, October 23, 2012


Great Article by Wall St Journal
Entitled "The Unreality of the Last Four Years" In the 1967 film "A Guide for the Married Man," a husband, played by a peerless Walter Matthau, is given lessons in ways to cheat on his wife safely. The most essential rule: "Deny! Deny! Deny!"—no matter what. In an instructive scene, he's shown a wife undone by shock, and screaming, with reason: She has just walked in on her husband making love to a glamorous stranger. "What are you doing," she wails, "who is that woman?" "What woman, where?" the husband serenely counters, as he and the tart in question get out of bed and calmly dress. So the scene proceeds, with the distraught wife pointing to the woman she clearly sees before her, while her husband, unruffled, continues to look blankly at her, asking, "What woman?" Confused by her spouse's unblinking assurance, she gives up. Two minutes later she's asking him what he'd like for dinner. For much of the past four years, the Obama administration's propensity for asserting views of reality wildly at odds with those evident to most rational citizens has looked increasingly like a page from that film script. All administrations conceal, falsify and tell lies—this is understood—but there's no missing the distinctive quality of the prevaricating issuing from the White House in these four years. It's a quality on vivid display now in the administration's mesmerizing narrative of the assault on the U.S. consulate in Libya. Here's a memorable picture, its detail brutally illuminating, of Obama and company in crisis mode over their conflicting stories about who knew what when. The resulting costs to truth-telling and sanity, or even the appearance thereof, are clear. Nor can we forget the strong element of farce—think U.N. Ambassador Susan Rice on those five Sunday talk shows, reciting with unflagging fervor that official talking point regarding mob violence and a YouTube video. Farce, but no one is laughing. Team Obama clung to its original story—the attack had come spontaneously at the hands of a mob enraged by that now famous video insulting to the Prophet—long after it was clear that it had been an organized terrorist assault by an al Qaeda affiliate. By Tuesday's debate, we saw a Barack Obama in high dudgeon over suggestions that his office might have deliberately misrepresented the facts. It was, he fumed, an intolerable insult that such charges could have been made about him, the president who had had to receive the bodies of the slain Americans—and who then had to set about getting to the bottom of this murderous terror assault. Profound and urgent concerns indeed—which, the president neglected to say, had not prevented him from jetting off to his fundraiser in Las Vegas the day after the murders. His administration was not given to politicizing serious matters, the president sternly informed the nation in that second debate: "That's not what we do." Good to know. Americans might otherwise have gotten the wrong impression in the past four years, not least from Attorney General Eric Holder, who heads the most openly politicized Justice Department in the nation's history. Among his more recent noteworthy pronouncements, this one relevant to the coming election, Mr. Holder declared that photo ID requirements intended to prevent voting fraud were nothing less than a "poll tax." He was referring to an infamous institution from the days of Jim Crow, whose aim was to suppress black voting. Mr. Holder—so famously fastidious about group sensibilities that he has never been able to bring himself to utter any description identifying a terrorist as Muslim—has apparently had no inhibitions about smearing whole segments of the population as racists. Mr. Obama's outrage notwithstanding, the administration's prolonged efforts to muddle the picture of the Benghazi attack raised proper suspicions. The Obama team's instant response—that Republicans were attempting to politicize a tragedy—was entirely characteristic. If ever a story screamed its politicized nature, it was the administration's Scheherazade-like tale, now five weeks old and rolling on, about that Sept. 11 assault. A tale that left little doubt of its motivation: fear of the impact, so close to the election, of a successful terrorist attack—the clear indication that al Qaeda was not, as claimed, on the run. It didn't hurt, of course, that a crude video like the one insulting to Islam is exactly the kind of fodder to which the Obama ministry is partial: Here was an opportunity for right-minded condemnation of bigotry, and if that bigotry was directed at Muslims, all the more opportune. It would be hard to say which member of the Obama administration most invoked the power and influence of that bit of film, officially to be known, now and forever, as the disgusting and reprehensible video. More and more clearly, the Obama administration has put its faith in the view that the governed, who must be told what is best for their lives, whether they want it or not (see ObamaCare), can also be told that they have not seen what they've seen, have not heard what their ears clearly told them. When the "if you've got a business, you didn't build that" speech proved to be a political land mine, team Obama instantly charged malicious, out-of-context distortion. The president was only talking about—infrastructure! About government-built roads vital for businesses, transportation, etc. It isn't likely that Americans who had heard the Obama address failed to understand, rightly, its sneering tone directed at those who believed they had a right to think they were responsible for their own success. Not likely that they didn't notice the icy thrust of those words, "I'm always struck by people who feel, 'Well, it must be because I'm just so smart.'" The president had revealed, with unforgettable clarity, his contempt for faith in individual enterprise—a value Americans of every station hold dear. So clear was this contempt, the Republicans knew enough to make it the Day One theme of their convention—the only good day. Democratic Party representatives meanwhile went forward en masse to charge the Republicans with dishonesty. In the books yet to be written about this presidency, the Obama administration's exceptional readings of reality will deserve an honored place, and a large one. One that should also acknowledge the fact that, in the end, the American people inevitably recognize the difference between lies and truth, illusion and the real thing. The most telling example of this capacity—the October surprise that shouldn't have been surprising—came with the first presidential debate. The nation saw a superbly cogent Mitt Romney, speaking to them in terms instantly recognizable, words without artifice that addressed their real lives. Viewers saw the life in him, the play of mind, felt the sense of powerful will—that of a leader. It didn't matter all that much that the president looked most unpresidential, a man lost. What mattered was the other man before them, who had brought home to Americans what they had been missing the past four years. Not surprisingly, when the debate's effects were clear, Obama squads were again deployed to cry fraud. Mr. Romney, we were told, had done nothing but lie. This would now be the official story. It would have no effect. People had seen what they had seen and that would not be changed, not by an improved, fighting Obama as he was last Tuesday, or by a heroically transformed one on Monday night. Ms. Rabinowitz is a member of the Journal's editorial board.
Saturday, October 20, 2012
Hoisington: Proof the Fed Is Causing Inflation, Not Growth
The Hoisington Quarterly Review and Outlook is one of the
cornerstones of my reading on where the economy is headed. Van
Hoisington and Lacy Hunt do a masterful job of turning data points into
cogent, well-argued themes.
This month they waste no time in dissecting the Fed’s recent move to
QE3 and similar efforts in Europe, arriving at the conclusion that
“While prices for risk assets have improved, governments have not been
able to address underlying debt imbalances. Thus, nothing suggests that
these latest actions do anything to change the extreme over-indebtedness
of major global economies.”
Their expectation: global recession. The only issue left to sort out, they say, is How deep will the downturn be?
They make the interesting observation that with each injection of
liquidity by the Fed, commodity prices have surged: “During QE1 &
QE2 wholesale gasoline prices jumped 30% and 37%, respectively, and the
Goldman Sachs Commodity Food Index (GSCI-Food) rose 7% and 22%,
respectively. From the time the press reported that the Fed was moving
toward QE3, both gasoline and the GSCI Food index jumped by 19%, through
the end of the 3rd quarter.”
The QE picture gets even muddier. The unintended consequence of the Fed’s actions, say Lacy and Van, has been to actually slow economic activity:
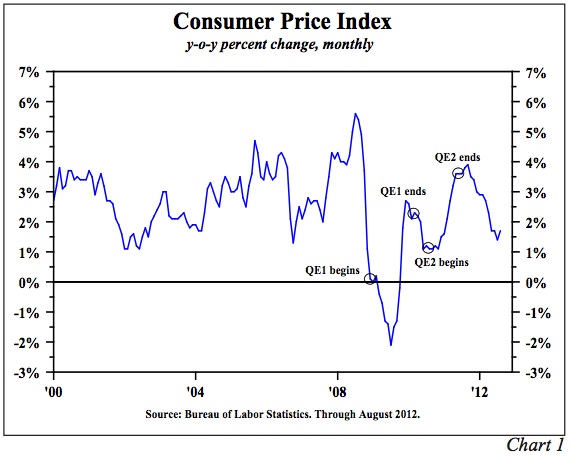
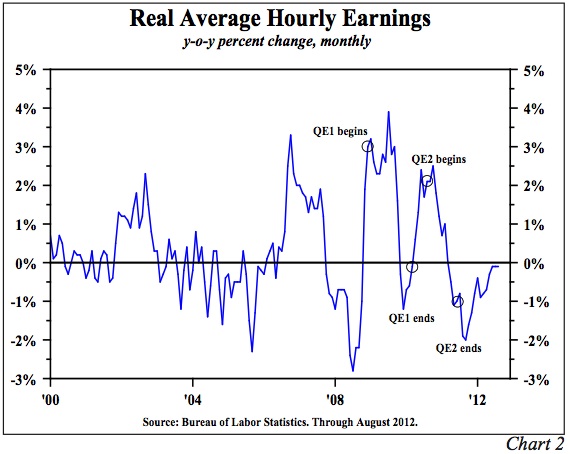
“The CPI rose significantly in QE1 and QE2 (Chart 1). These price
increases had a devastating effect on worker's incomes (Chart 2). Wages
did not immediately respond to commodity price changes; therefore, there
was an approximate 3% decline in real average hourly earnings in both
instances. It is true that stock prices also rose along with commodity
prices (S&P plus 36% and 24%, respectively, in QE1 and QE2).
However, median households hold a small portion of equities, and thus
received minimal wealth benefit.”
They proceed to tear apart the wealth effect that the Fed is banking on
to restimulate the economy, drawing on several solid studies. They also
make the key point that “When the Fed actions lead to higher food and
fuel prices, the shock wave reverberates around the world, with many
foreign economies being hit adversely. When prices of basic necessities
rise, the greatest burden is on those with the lowest incomes since more
of their budget is allocated to the basic necessities such as food and
fuel.”
The next few years are not going to be pretty. We’re looking right into
the teeth of a rolling global deleveraging recession—the End Game, I’ve
called it. And the decisions we make in the next couple years about how
to handle our debts and budget deficits—here in the U.S., in Europe, in
China and Japan, and elsewhere—are going to be absolutely crucial.
Hoisington Investment Management Company (www.hoisingtonmgt.com)
is a registered investment advisor specializing in fixed-income
portfolios for large institutional clients. Located in Austin, Texas,
the firm has over $4 billion under management, composed of corporate and
public funds, foundations, endowments, Taft-Hartley funds, and
insurance companies.
My daughter Abbi is coming into town tonight from Tulsa with her
fiancé, and most of the family will gather over the weekend for dinners
and fun. And her twin Amanda is expecting, so another grandchild is in
the future as well. Family and friends are among the few permanent
fixtures in a world that seems to change almost weekly.
I was with Pat Cox of Breakthrough Technology Alert on Tuesday
night. We watched the debate and then went deep into the night talking
about the future. And got up the next day and did the same between
meetings. We ended up doing a tag team that night for Hedge Fund Cares,
which raised a lot of money to help abused children. I talked about the
global landscape (which was not so upbeat) and he talked about the
changes we see in the biotech world; and we then both answered
questions, which was more fun, as we got to think about the marvelous
the future that is shaping up. Such totally amazing things are
happening. I am really quite the optimist over the longer term.
Have a great weekend, and look for your next Thoughts from the Frontline in your inbox Monday.
Your bullish on the future but bearish on governments analyst,
John Mauldin, Editor
Outside the Box
Hoisington Investment ManagementOutside the Box
Quarterly Review and Outlook
Third Quarter 2012
Growth Recession
Entering the final quarter of the year, domestic and global economic
conditions are extremely fragile. Across the globe, countries are in
outright recession, and in some instances where aggregate growth is
holding above the zero line, manufacturing sectors are contracting. The
only issue left to determine is the degree of the downturn underway.
International trade is declining, so weaknesses in different parts of
the world are reinforcing domestic deteriorations in economies
continents away. With this global slump at hand, a highly relevant
question is whether the U.S. can escape a severe recession in light of
the following:
a) the U.S. manufacturing sector that paced domestic economic growth over the past three years has lapsed into recession;
b) real income and the personal saving rate have been slumping in the face of an interim upturn in inflation, and
c) aggregate over-indebtedness, which is the dominant negative force in
the economy, has continued to move upward in concert with flagging
economic activity.
New government initiatives have been announced, particularly by central
banks, in an attempt to counteract deteriorating economic conditions.
These latest programs in the U.S. and Europe are similar to previous
efforts. While prices for risk assets have improved, governments have
not been able to address underlying debt imbalances. Thus, nothing
suggests that these latest actions do anything to change the extreme
over-indebtedness of major global economies.
To avoid recession in the U.S., the Federal Reserve embarked on
open-ended quantitative easing (QE3). Importantly, the enactment of QE3
is a tacit admission by the Fed that earlier efforts failed, but this
action will also fail to bring about stronger economic growth.
Commodity Market Reactions
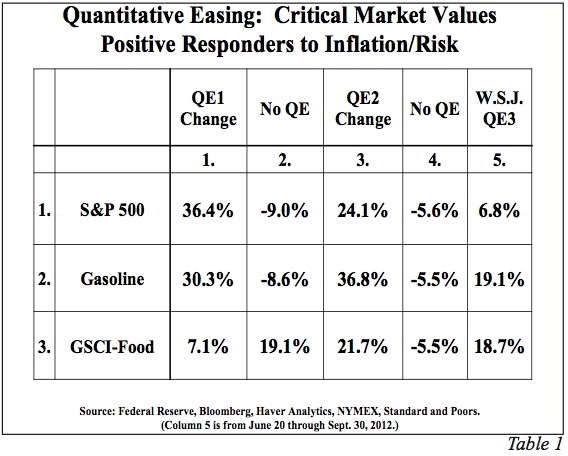
Commodity markets have risen in reaction to the Federal Reserve’s
liquidity injections into the banking sector (Table 1). From the time
the press reported that the Fed was moving toward QE1 & QE2
commodity prices surged. During QE1 & QE2 wholesale gasoline prices
jumped 30% and 37%, respectively, and the Goldman Sachs Commodity Food
Index (GSCI-Food) rose 7% and 22%, respectively. From the time the
press reported that the Fed was moving toward QE3, both gasoline and the
GSCI Food index jumped by 19%, through the end of the 3rd quarter.
Two theoretical considerations account for the rise in commodity prices
during QE3. The first is the expectations effect. When the Fed says
they want higher inflation, the initial reaction of the markets is to
“go with”, rather than fight the Fed. The second linkage, which is the
expanded availability of funds used for collateral (margin), was
identified and subsequently confirmed by Newedge economist, Dr. Rod
McKnew, who stated, “In a world of advanced derivatives, high cash
balances are not required to take speculative positions. All that is
required is that margin requirements be satisfied.” Thus, when the Fed
massively expanded reserve balances in QE1 and QE2, margin risk was
minimized for those market participants who wished to take positions
consistent with the Fed’s goal of higher inflation, and who had either
direct or indirect access to the Fed’s hugely inflated reserve
balances. The April 22, 2011 issue of Grant’s Interest Rate Observer
documented support for McKnew’s insight. They asked Darrell Duffie, the
Dean Witter Distinguished Professor of Finance at the Graduate School
of Business at Stanford University, whether excess reserves could serve
as collateral for futures and derivatives transactions. Dr. Duffie’s
answer was “acceptable collateral is a matter of private contract, but
reserve deposits are virtually always acceptable.”
Devastation for Households
The unintended consequence of these Federal Reserve actions, however,
is to actually slow economic activity. The CPI rose significantly in
QE1 and QE2 (Chart 1). These price increases had a devastating effect
on worker's incomes (Chart 2). Wages did not immediately respond to
commodity price changes; therefore, there was an approximate 3% decline
in real average hourly earnings in both instances. It is true that
stock prices also rose along with commodity prices (S&P plus 36% and
24%, respectively, in QE1 and QE2). However, median households hold a
small portion of equities, and thus received minimal wealth benefit.
Wealth Effect
Despite the miserable economic results in QE1 and QE2, we now have
QE3. Fed Chair Ben Bernanke and other Fed advocates believe the “wealth
effect” of QE3 will bring life to the economy. The economics
profession has explored this issue in detail. Sydney Ludvigson and
Charles Steindel in How Important is the Stock Market Effect on Consumption
in the FRBNY Economic Policy Review, July 1999 write: “We find, as
expected, a positive connection between aggregate wealth changes and
aggregate spending. Spending growth in recent years has surely been
augmented by market gains, but the effect is found to be rather unstable
and hard to pin down. The contemporaneous response of consumption
growth to an unexpected change in wealth is uncertain, and the response
appears very short-lived.” More recently, David Backus, economic
professor at New York University found that the wealth effect is not
observable, at least for changes in home or equity wealth.
A 2011 study in Applied Economic Letters entitled, Financial Wealth Effect: Evidence from Threshold Estimation
by Sherif Khalifa, Ousmane Seck and Elwin Tobing found “a threshold
income level of almost $130,000, below which the financial wealth effect
is insignificant, and above which the effect is 0.004.” This means a $1
rise in wealth would, in time, boost consumption by less than one-half
penny.
These three studies show that the impact of wealth on spending is
miniscule—indeed, “nearly not observable.” How the Fed expects the U.S.
to gain any economic traction from higher stock prices when rising
commodity prices are curtailing real income and spending is puzzling.
This is particularly relevant when econometricians have estimated that
for every dollar of gained real income, consumption will rise by about
70 cents. Conversely, the Fed actions are causing real incomes to
decline, which has a 70-cent negative impact on spending for every
dollar loss. Compare that with the 0.004 positive impact on spending
for every one-dollar increase in wealth. Former Fed Chairman, Paul
Volcker, summarized the new Fed initiative as sufficiently and
succinctly as anyone when he stated that another round of QE3 “is
understandable, but it will fail to fix the problem.”
An International Corollary
The unintended consequences of QE3 could also serve to worsen and
undermine global economic conditions already under considerable duress.
When the Fed actions lead to higher food and fuel prices, the shock
wave reverberates around the world, with many foreign economies being
hit adversely. When prices of basic necessities rise, the greatest
burden is on those with the lowest incomes since more of their budget is
allocated to the basic necessities such as food and fuel. Thus, a jump
in daily essentials has a more profound negative impact on living
standards in economies with lower levels of real per capita income.
Can the Fed Create Demand?
Can all the trillions of dollars of reserves being added to the banking
system move the economy forward enough to eventually create a higher
level of aggregate spending? Our analysis of the aggregate demand curve
and its determinants indicate they cannot. The question is whether
monetary actions can shift this aggregate demand (AD) curve out to the
right from AD0 to AD1 (Chart 3). If this were possible, then indeed the
economy would shift to a higher level of prices and real GDP.
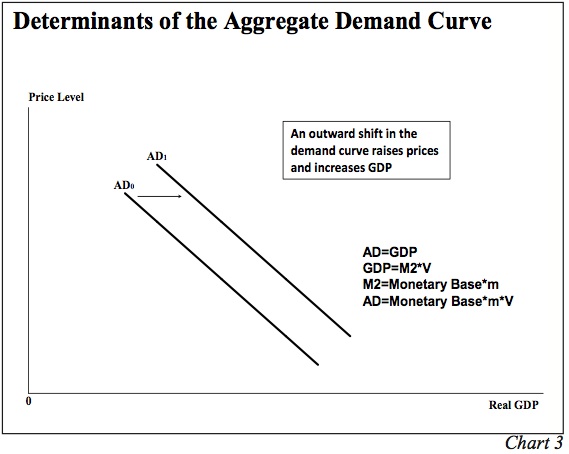
The AD curve is equal to planned expenditures for nominal GDP since
every point on the curve is equal to the aggregate price level (measured
on the vertical axis of the graph), multiplied by real GDP (measured on
the horizontal axis of the graph). We know that GDP is equal to money
times its turnover or velocity, which is called the equation of exchange
as developed by Irving Fisher (Nominal GDP = M*V).
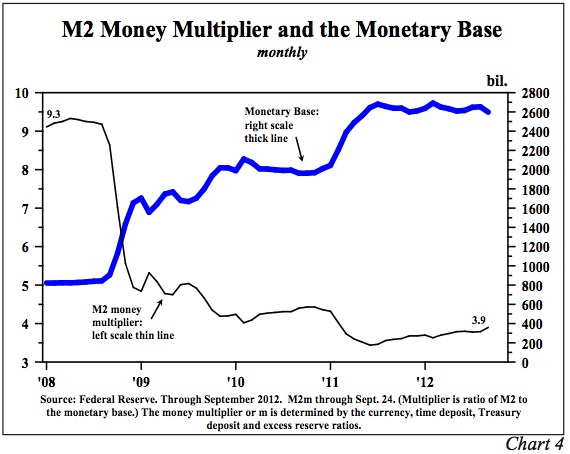
Deconstructing this formula, M (or M2) is comprised of the monetary
base (currency plus reserves) times the money multiplier (m). The
Federal Reserve has control over the monetary base since its balance
sheet is the dominant component of the monetary base. However, the Fed
does not directly control the money supply. The decisions of the
depository institutions and the non-bank public determine the money
multiplier (m). M2 thus equals the monetary base multiplied by the
money multiplier. The monetary base, also referred to as high powered
money, has exploded from $800 billion in 2008, to $2.6 trillion
currently, but the money multiplier has collapsed from 9.3 to 3.9 (Chart
4). Therefore, the money supply has risen significantly less than the
increase in the Fed’s balance sheet, with the result that neither rapid
gains in real GDP nor inflation were achieved. Indeed, with the
exception of transitory episodes, inflation remains subdued and the gain
in GDP in the three years of this expansion was the worst of any
recovery period since World War II.
The other element that is required for the Fed to shift the aggregate
demand curve outward is the velocity or turnover of money over which
they also have no control. During all of the Fed actions since 2008 the
velocity of money has plummeted and now stands at a five decade low
(Chart 5).
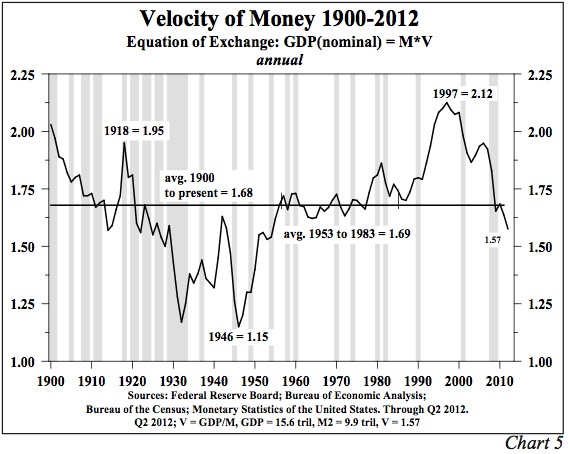
The consequence of the Fed’s lack of control over the money multiplier
and velocity is apparent. The monetary base has surged 3.3 times in
size since QE1. Nominal GDP, however, has grown only at an annual rate
of 3%. This suggests they have not been able to shift the aggregate
demand curve outward. Nor, with these constraints, will they be any
more successful in shifting that curve under the present open-ended
QE3. Increased aggregate demand and thus rising inflation is not on the
horizon.
[For a more complete discussion of the complexities of the movement
of the aggregate supply and aggregate demand curves please see the
APPENDIX.]
Treasury Bonds
As commodity prices rose initially in all the QE programs, long-term
Treasury bond yields also increased. However, those higher yields
eventually reversed and generally continued to ratchet downward,
reaching near record lows. The current Fed actions may be politically
necessary due to numerous demands for them to act to improve the clearly
depressed state of economic conditions. However, these policies will
prove to be unproductive. Economic fundamentals will not improve until
the extreme over-indebtedness of the U.S. economy is addressed, and this
is in the realm of fiscal, not monetary policy. It would be more
beneficial for the Fed to sit on the sidelines and try to put pressure
on the fiscal authorities to take badly needed actions rather than do
additional harm. Until the excessive debt issues are addressed, the
multi-year trend in inflation, and thus the long Treasury bond yields
will remain downward.
APPENDIX
One of the most important concepts in macroeconomics is aggregate
demand (AD) and aggregate supply (AS) analysis – a highly attractive
approach that is neither Keynesian, monetarist, Austrian, nor any other
individual school, but can be used to illustrate all of their main
propositions. However, before detailing the broader macroeconomics
associated with the movement of the AD and AS curves, it is important to
understand microeconomic supply and demand curves. This can best be
illustrated through the recent impact the Fed’s decisions had on
commodity prices. In the commodity market, like individual markets in
general, the demand curve is downward sloping, the supply curve is
upward sloping, and where they intersect determines the price of the
commodity and the quantity supplied/demanded. The micro-demand curve
slopes downward because as the price of an item rises, the quantity
demanded falls due to income and substitution effects (buyers can shift
to a substitute product). The micro-supply curve slopes upward since
producers will sell more at higher prices than lower ones.
Both supply and demand schedules are influenced by expectation,
fundamental, and liquidity considerations. When the Fed says that they
want faster inflation and that they are going to take steps to achieve
this objective, both economic theory and historical experiences indicate
that commodity prices will rise, at least transitorily (as seen with
the surge in commodity prices after the announcement of QE1, QE2 and
QE3). Information and liquidity available to the buyers is also
available to the suppliers, so by saying faster inflation is ahead,
suppliers are encouraged to reduce or withhold current production or
inventories, moving the supply curve inward. Thus, in the commodity
market, the Fed action spurs an outward shift in the micro-demand curve
along with an inward shift of the micro-supply curve, producing higher
prices and lower quantities. These microeconomic developments transmit
to the broader economy, which we will now trace through AD and AS
curves.
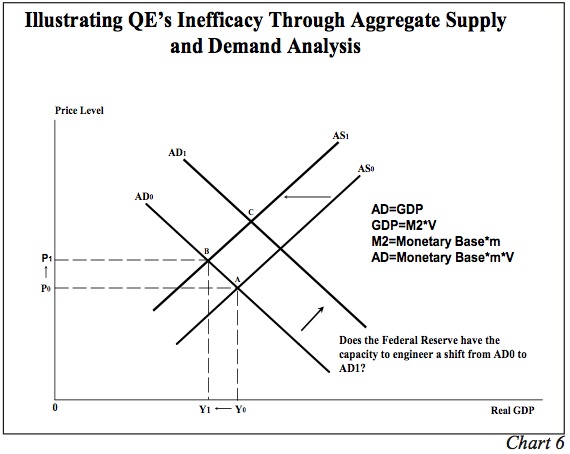
The AD curve slopes downward and indicates the amount of real GDP that
would be purchased at each aggregate price level (Chart 6). Aggregate
demand varies inversely with the price level, so if the price level
moves upward from P0 to P1, real GDP declines from Y0 to Y1. When the
price level rises, real wages, real money balances and net exports
worsen, thereby reducing real GDP. The rationale for the downward
sloping AD curve is thus quite different from the sloping of the
micro-demand curve since substitution effects are not possible when
dealing with aggregate prices. In order to improve real GDP with a
rising price level, the AD curve would need to be shifted outward and to
the right (from AD0 to AD1). And as detailed in the letter, the Fed is
not capable of shifting the entire AD curve.
The AS curve slopes upward and indicates the quantity of GDP supplied
at various price levels. The positive correlation between price and
output in micro and macroeconomics is the same since the AS curve is the
sum of all supply curves across all individual markets. When Fed
policy announcements shock commodity markets, the AS curve shifts inward
and to the left (from AS0 to AS1). This immediately causes a reduction
in real GDP (the difference between Y0 and Y1) as the price increases
by the difference between P0 and P1 (also Chart 6). Furthermore, as
discussed in the letter, lower GDP as a result of higher prices reduces
the demand for labor and widens the output gap, setting in motion a
negative spiral.
For Fed policy to improve real GDP, actions must be taken that either
(1) shift the entire demand curve outward (to the right), or (2) do not
cause an inward shift of the AS curve that induces an adverse movement
along the AD curve. Accordingly, the Fed is without options to improve
the pace of economic activity.
Subscribe to:
Posts (Atom)