Wednesday, October 30, 2013
More on VWAP
another explanation of VWAP:
In finance, volume-weighted average price (VWAP) is the ratio of the value traded to total volume traded over a particular time horizon (usually one day). It is a measure of the average price a stock traded at over the trading horizon.[1]
VWAP is often used as a trading benchmark by investors who aim to be as passive as possible in their execution. Many pension funds, and some mutual funds, fall into this category. The aim of using a VWAP trading target is to ensure that the trader executing the order does so in-line with volume on the market. It is sometimes argued that such execution reduces transaction costs by minimizing market impact costs (the additional cost due to the market impact, i.e. the adverse effect of a trader's activities on the price of a security).
VWAP can be measured between any two points in time but is displayed
as the one corresponding to elapsed time during the trading day by the
information provider.
VWAP is often used in algorithmic trading. Indeed, a broker
may guarantee execution of an order at the VWAP and have a computer
program enter the orders into the market in order to earn the trader's commission and create P&L.
This is called a guaranteed VWAP execution. The broker can also trade
in a best effort way and answer to the client the realized price. This
is called a VWAP target execution; it incurs more dispersion in the
answered price compared to the VWAP price for the client but a lower
received/paid commission. Trading algorithms that use VWAP as a target
belong to a class of algorithms known as volume participation algorithms.
Table of Contents
| ||||||||||||||||||||||||||||||||||||||||||
Formula
VWAP is calculated using the following formula:
 is Volume Weighted Average Price;
 is price of trade
 ;
 is quantity of trade ;
- is each individual trade that takes place over the defined period of time, excluding cross trades and basket cross trades.[2]

VWAP Explained
Summary
This custom intraday Volume-Weighted Average Price (VWAP) indicator provides estimated current and historical intraday VWAP values. The indicator plots as many as the last four daily VWAPs, as well as the real-time VWAP on the current session of the analyzed security. The historical VWAPs can serve as support and resistance lines as the current session's price action unfolds and can offer valuable information for traders. The intraday VWAP is reset at the beginning of each new trading session and the historical VWAP lines are color coded for visual differentiation of the age of each VWAP line.Introduction
VWAP is a ratio widely used in trading. It is based on the price of the security and its volume over a specified time period (usually one day). The numerator is the sum of the security's price over the specified time period multiplied by the corresponding volume; the denominator is the total shares/contracts traded for the time period. The formula for the VWAP can be written as follows:
where:
PVWAP = Volume Weighted Average Price
Pj = price of trade j
Qj = quantity of trade j
j = each individual trade that takes place over the defined period of time
Source: http://en.wikipedia.org/wiki/VWAP
Background
VWAP has numerous applications in the trading world. It is often used in algorithmic trading, more specifically in volume-participation algorithms. For example, a broker may guarantee the execution of a trade at the VWAP price (known as a Guaranteed VWAP execution). A broker may also offer a VWAP target execution where the broker makes a best effort to execute near the VWAP.VWAP is also used as a trading benchmark by investors who are not worried about the timing of the trade, but who are concerned about the adverse impact of their trades on the price of the security. The goal is to execute orders in-line with the volume of the market. Many pension funds and some mutual funds fall into this category.
The performance of passive traders is sometimes measured according to the VWAP. Long entry prices that are lower than the VWAP are considered favorable, while entries above the VWAP are considered unfavorable. These non-discretionary trades take place with a general disregard for timing. In this case, VWAP is used to calculate trading costs, since the average entry price would be compared to the VWAP benchmark price. This is the main reason why some argue that using the VWAP as a target reduces transaction costs.
The VWAP calculation can take numerous other forms in practice. In addition to the standard definition above, traders may use VWAP excluding their own transactions, non-block VWAP, VWAP proxies when tick data is unavailable, and value-weighted average for volatile markets in which prices weighted by dollar value of trade are used instead of share/contract volume.
Current Application
VWAP can also be a useful tool for short-term discretionary traders and many different strategies can employ this measurement. One simple well-known strategy is to wait for the price to pierce through the VWAP to the upside when a long position is sought and when the trader is looking for buyers to regain control, since a breakout above VWAP may show upside momentum. The core idea is that the current VWAP and past VWAPs can act as potential support and resistance levels.Most trading applications only show the current day's VWAP. This is mainly because historical VWAPs require enormous amounts of data, since all the tick and volume data for the different sessions would need to be referenced. One solution is to approximate the historical VWAPs using 1-minute intraday data, cutting down dramatically on the amount of historical data needed. The resulting VWAPs are not exact, but are very close to the actual values.

Indicator Inputs
| Name | Value | Description |
|---|---|---|
| TodaysVWAPColor | Red | Color used for the current intraday VWAP |
| YesterdaysVWAPCol | Blue | Color used for yesterday's final VWAP value |
| TwoDaysAgoVWAPCol | Yellow | Color used for the final VWAP value of 2 days ago |
| ThreeDaysAgoVWAPCol | Cyan | Color used for the final VWAP value of 3 days ago |
| ThreeDaysAgoVWAPCol | Magenta | Color used for the final VWAP value of 4 days ago |
Indicator Construction
The current intraday VWAP is approximated using a 1-minute intraday chart and the formula listed in the beginning of this paper. The intraday VWAP is displayed using a red line (TodaysVWAPColor input). Depending on how much data is loaded into the chart, the maximum number of VWAPs that can be seen is five at any one time (current VWAP plus previous four daily VWAPs). The last four historical daily VWAPs are color coded using user-defined colors (YesterdaysVWAPCol, TwoDaysAgoVWAPCol, ThreeDaysAgoVWAPCol, and FourDaysAgoVWAPCol inputs) in order to identify how old each VWAP is no matter where on the chart you are looking.The indicator recognizes whether pre- and/or post-market data is used for equities and the VWAP values are not reset after the pre-market session ends or when the post-market session starts. Therefore, if pre- and post-market data is used, each one of the five different VWAPS includes the data from its pre- and post-market session in the calculations. A 1-minute intraday interval is recommended to better estimate the VWAPs; however, depending on your willingness to accept a margin of error, you may want to experiment with slower intervals (i.e., 5 minutes). The indicator will be able to detect pre- and/or post-market equity data no matter which intraday interval is used (i.e., 5-minute intraday interval).
For additional information on the indicator construction, please refer to the comments inside the EasyLanguage® document.
After you have imported the indicator from the attached .eld file, you can use the workspace provided. Please look for "IntradayVWAPs" in your list of indicators to insert this indicator on a new chart.
Analysis
Viewing this custom VWAP indicator on an intraday chart reveals that the different VWAP lines often act as resistance and support lines. A VWAP line that was acting as resistance often becomes support once penetrated, while a VWAP line acting as support often becomes resistance once penetrated. The different VWAP lines can also serve as target lines intraday when the price action is caught between lines.As with any other technical analysis tool, the VWAP lines can work well at times and not so well at other times. A VWAP on stronger-than-average daily volume and/or different VWAPs near the same price may provide a higher probability of acting as potential support or resistance. It might also be interesting to use other technical analysis tools in conjunction with the VWAP lines in order to better discern which line might be providing a stronger support or resistance level.
As described in the Indicator Construction section, the indicator works with, or without pre- and/or post-market equity data. The indicator can be applied to any security where volume is accessible. For example, the indicator works with futures, such as the S&P E-mini futures contract. In that case, the indicator is able to recognize that 17:00 U.S. Central Time on Sunday is the opening time for Monday's session and the VWAP is then reset on the first bar after 15:30 U.S. Central Time.
Conclusion
This custom intraday VWAP indicator sheds light on an area of analysis that is often obscured by the inaccessibility of the needed data. Using intraday data of a short interval provides active traders with VWAP values accurate enough to be of practical use. The different VWAP lines often act as support and resistance lines for the considered security and can offer valuable information for traders.Potential future versions of this indicator may include the flexibility to specify an exact time period to take into consideration for the VWAP calculations. In addition, inputs could be made available to create custom sessions to consider for the VWAP calculations. For example, maybe only the first and last hours of the regular session should be included in the VWAP calculation. Lastly, the width of the VWAP lines could be made to vary depending on the daily volume for additional visual assistance as to which line might be relatively more important. Stay tuned!
Attachments
 Intraday VWWAPs
In order to open the sample workspaces provided, you may first need to import the custom EasyLanguage® file with the extension .eld. Copy the attached .eld file and workspaces to your computer. Then import the indicators or strategies by double-clicking on the EasyLanguage .eld file. This will automatically start the TradeStation import wizard. Click 'Next' until the Analysis Techniques and/or strategies have been imported. The indicators are now available and you can now open the provided workspaces. Other supportive documents or files may also be attached to this e-mail.
All support, education and training services and materials on the TradeStation Securities website are for informational purposes and to help customers learn more about how to use the power of TradeStation software and services. No type of trading or investment advice is being made, given or in any manner provided by TradeStation Securities or its affiliates.
This material may also discuss in detail how TradeStation is designed to help you develop, test and implement trading strategies. However, TradeStation Securities does not provide or suggest trading strategies. We offer you unique tools to help you design your own strategies and look at how they could have performed in the past. While we believe this is very valuable information, we caution you that simulated past performance of a trading strategy is no guarantee of its future performance or success. We also do not recommend or solicit the purchase or sale of any particular securities or derivative products. Any symbols referenced are used only for the purposes of the demonstration, as an example ---- not a recommendation.
Finally, this material may discuss automated electronic order placement and execution. Please note that even though TradeStation has been designed to automate your trading strategies and deliver timely order placement, routing and execution, these things, as well as access to the system itself, may at times be delayed or even fail due to market volatility, quote delays, system and software errors, Internet traffic, outages and other factors.
Another view from Stockcharts.com:
Introduction
Volume-Weighted Average Price (VWAP) is exactly what it sounds like: the average price weighted by volume.
VWAP equals the dollar value of all trading periods divided by the
total trading volume for the current day. Calculation starts when
trading opens and ends when trading closes. Because it is good for the
current trading day only, intraday periods and data are used in the
calculation.
Tick versus Minute
Traditional VWAP is based on tick data. As one can imagine, there are
many ticks (trades) during each minute of the day. Active securities
during active time periods can have 20-30 ticks in one minute alone.
With 390 minutes in a typical stock exchange trading day, many stocks
end up with well over 5000 ticks per day. There are over 5000 stocks
traded every day and these ticks start adding up exponentially. Needless
to say, tick-data is very resource intensive.

Instead of VWAP based on tick data, StockCharts.com offers intraday VWAP based on intraday periods (1, 5, 10, 15, 30 or 60 minute). Note that VWAP is not defined for daily, weekly or monthly periods due to the nature of the calculation (see below).
Instead of VWAP based on tick data, StockCharts.com offers intraday VWAP based on intraday periods (1, 5, 10, 15, 30 or 60 minute). Note that VWAP is not defined for daily, weekly or monthly periods due to the nature of the calculation (see below).
Calculation
There are five steps involved in the VWAP calculation. First, compute
the typical price for the intraday period. This is the average of the
high, low and close {(H+L+C)/3)}. Second, multiply the typical price by
the period's volume. Third, create a running total of these values. This
is also known as a cumulative total. Fourth, create a running total of
volume (cumulative volume). Fifth, divide the running total of
price-volume by the running total of volume.

The example above shows 1-minute VWAP for the first 30 minutes of trading in IBM. Dividing cumulative price-volume by cumulative volume produces a price level that is adjusted (weighted) by volume. The first VWAP value is always the typical price because volume is equal in the numerator and the denominator. They cancel each other out in the first calculation. The chart below shows 1-minute bars with VWAP for IBM. Prices ranged from 127.36 on the high to 126.67 on the low for the first 30 minutes of trading. It was actually a pretty volatile first 30 minutes. VWAP ranged from 127.21 to 127.09 and spent its time in the middle of this range.

Cumulative(Volume x Typical Price)/Cumulative(Volume)
The example above shows 1-minute VWAP for the first 30 minutes of trading in IBM. Dividing cumulative price-volume by cumulative volume produces a price level that is adjusted (weighted) by volume. The first VWAP value is always the typical price because volume is equal in the numerator and the denominator. They cancel each other out in the first calculation. The chart below shows 1-minute bars with VWAP for IBM. Prices ranged from 127.36 on the high to 126.67 on the low for the first 30 minutes of trading. It was actually a pretty volatile first 30 minutes. VWAP ranged from 127.21 to 127.09 and spent its time in the middle of this range.
Characteristics
Like moving averages, VWAP lags price because it is an average based on
past data. The more data there is, the greater the lag. A stock has
been trading for some 331 minutes by 3PM. As a cumulative "average",
this indicator is akin to a 330 period moving average. That is a lot of
past data. The 1-minute VWAP value at the end of the day is often quite
close to the ending value for a 390 minute moving average. Both moving
averages are based on the 1 minute bars for that day. At the close, both
are based on 390 minutes of data (one full day). One cannot compare the
390 minute moving average to VWAP during the day though. A 390 minute
moving average at 12:00PM will include data from the previous day. VWAP
will not. Remember, VWAP calculations start fresh at the open and end at
the close. 150 minutes of trading have elapsed by 12:00PM. Therefore,
VWAP at 12:00 would need to be compared with a 150 minute moving
average.

Despite this lag, chartists can compare VWAP with the current price to determine the general direction of intraday prices. It works similar to a moving average. In general, intraday prices are falling when below VWAP and intraday prices are rising when above VWAP. VWAP will fall somewhere between the day's high-low range when prices are range bound for the day. The next three charts show examples of rising, falling and flat VWAP.


Despite this lag, chartists can compare VWAP with the current price to determine the general direction of intraday prices. It works similar to a moving average. In general, intraday prices are falling when below VWAP and intraday prices are rising when above VWAP. VWAP will fall somewhere between the day's high-low range when prices are range bound for the day. The next three charts show examples of rising, falling and flat VWAP.
Uses for VWAP
VWAP is used to identify liquidity points. As a volume-weighted price
measure, VWAP reflects price levels weighted by volume. This can help
institutions with large orders. The idea is not to disrupt the market
when entering large buy or sell orders. VWAP helps these institutions
determine the liquid and illiquid price points for a specific security over a very short time period.
VWAP can also be used to measure trading efficiency. After buying or selling a security, institutions or individuals can compare their price to VWAP values. A buy order executed below the VWAP value would be considered a good fill because the security was bought at a below average price. Conversely, a sell order executed above the VWAP would be deemed a good fill because it was sold at an above average price.
VWAP can also be used to measure trading efficiency. After buying or selling a security, institutions or individuals can compare their price to VWAP values. A buy order executed below the VWAP value would be considered a good fill because the security was bought at a below average price. Conversely, a sell order executed above the VWAP would be deemed a good fill because it was sold at an above average price.
Conclusions
VWAP serves as a reference point for prices for one day. As such, it is best suited for intraday analysis.
Chartists can compare current prices with the VWAP values to determine
the intraday trend. VWAP can also be used to determine relative value.
Prices below VWAP values are relatively low for that day or specific
time. Prices above VWAP values are relatively high for that day or
specific time. Keep in mind that VWAP is a cumulative indicator,
which means the number of data points progressively increases
throughout the day. On a 1-minute chart, IBM will have 90 data
points (minutes) by 11AM, 210 data points by 1PM and 390 data points by
the close. The number dramatically increases as the day extends. This is
why VWAP lags price and this lag increases as the day extends.
SharpCharts
Volume-Weighted Average Price (VWAP) can be plotted as an "overlay"
indicator on Sharpcharts. After entering the security symbol, choose an
"intraday" period and a "range." This can be for 1 day or "fill the
chart." Chartists looking for more detail can choose "fill the chart."
Chartist looking for general levels can choose 1 day. VWAP can be
plotted over more than one day, but the indicator will jump from its
prior closing value to the typical price for the next open as a new
calculation period begins. Also note that VWAP values can sometimes fall
off the price chart. VWAP at 45.5 will be show up on a chart with a
price range from 45.8 to 47. Chartists sometimes need to extend the
range to a full day to see VWAP on the chart. The VWAP value is always
displayed at the top left of the chart. Click the chart below to see a
live example.


and still another, very simple, from Investopedia:
Definition of 'Volume Weighted Average Price - VWAP'A trading benchmark used especially in pension plans. VWAP is calculated by adding up the dollars traded for every transaction (price multiplied by number of shares traded) and then dividing by the total shares traded for the day.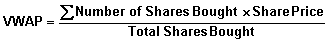 |
||||||
Investopedia explains 'Volume Weighted Average Price - VWAP'The theory is that if the price of a buy trade is lower than the VWAP, it is a good trade. The opposite is true if the price is higher than the VWAP. |

Terrible Asian Macro Data Sends Stocks to New Record Highs
Terrible economic news from Asia, and especially Japan, has sent stock
futures to a fresh all-time record high overnight. Find the logic in
that!

Stock Market Rise Tied to Collapse of Yen
Do
you see any pattern here? Why is the collapse of the Japanese Yen so
closely correlated to the rise in the US stock market? I wonder if
Japanese investors are beginning to panic over their own government's
QE-In-Perpetuity, and pull their money out to send to the US stock
market instead. I suspect they'll ultimately be disappointed. Note also
the sharp rise in stocks lately.
I have a rule that is really an observation of the financial markets:
Parabolic UP, parabolic DOWN! It means that when (stock) markets rise as
a parabolic rate, they are also prone to plunge at a similarly
parabolic rate!

DANGER! DANGER! BUBBLE WARNING FROM WORLD'S LARGEST FUNDS!
The
three largest asset management companies in the world have ALL now
warned that the Fed must begin removing it's QE stimulus to stop a
"bubble-like market". Executives of JP Morgan, PIMCO, and BlackRock, who
was the latest to warn of a bubble, are all now on the same page. Larry
Fink is head of BlackRock, the world's largest investment management
company, with more than $178 billion in assets as of 2010.
Meanwhile, the Fed is widely expected to INCREASE it tomorrow, instead!
Note
the verbiage that Fink is using. Words like "imperative",
"over-zealous" market, and "bubble-like markets" are ignored by the the
Fed Heads!
* FINK SAYS IT'S "IMPERATIVE" THAT THE FED BEGIN TO TAPER
* FINK CALLS MARKET `OVER-ZEALOUS'
* FINK SAYS THERE ARE "REAL BUBBLE-LIKE MARKETS AGAIN"
Saturday, October 26, 2013

Wednesday, October 23, 2013

Tuesday, October 22, 2013
How QE Is Likely to End and Why Commodities Are Still In a Secular Bull Market
from The Future Tense blog. I agree with every word of this:
We are rapidly approaching the point of "peak debt" globally. This has
been referred to here on this site as the end of the debt super cycle,
which began over 70 years ago.
The end of the debt super cycle means that many of the developed
economies that have used debt to create growth will no longer have the
ability to service their current debt or take on additional leverage.
The debt of a country can be seen at the individual (consumer),
corporate, banking, and government level.
In the United States the total debt in relation to the size of the
overall economy (debt to GDP ratio) reached 370% in 2008 before it
peaked.

This chart is certainly troublesome as it shows how far the United States still has remaining in the deleveraging process to bring the debt back to healthy/manageable levels. A reduction of just 20 basis points on this 370% debt to GDP ratio has put the country into a depression, temporarily masked by government spending and quantitative easing . Imagine what would occur if real a deleveraging took place? Here is the chart again with banking (financial) debt removed, showing the three remaining categories (GSE's are Fannie Mae, Freddie Mac, and Sallie Mae which can be considered part of government debt). Click for larger image.

Now for the scary part. The United States balance sheet looks like a time bomb waiting to explode (and it will), but viewed against the rest of the world the U.S. is not even the worst offender.
The following shows that the balance sheet for Japan, the U.K. and the Eurozone is far worse than the United States.

Does this make the United States debt situation more attractive? Of course not. It only shows that the current debt super cycle is a global phenomenon. Each one of these four developed regions (which make up the lion's share of global GDP) are approaching the point where they will have hit "peak debt," as the private portion of the U.S. balance sheet did in 2008.
The first question is always, with such staggering debt levels why has this not occurred already? This same question was posed for those who argued that the real estate market was in danger back in 2004 and 2005 as there appeared to be no issues on the surface.
The answer is that these countries have had the ability to roll existing debt (similar to refinancing a home) and borrow new debt (another buyer purchasing a home at a greater price) at ultra low interest rates. Just as the housing market reached its maximum point of leverage when interest rates rose, the same will occur on a much larger scale for the entire debt market across the developed world.
The next question is; Central banks are holding interest rates down with their QE programs in the United States, Europe, Japan, and the U.K. With the ability to print an endless amount of money, can't they just keep rates down forever?
The answer is no. Ultimately the market is going to overpower the central banks. This can occur in multiple ways. One way would be for investors to simply get nervous (or understand) that the debt they are holding fundamentally has no value as it is impossible for these debtors to ever repay. We could wake up any day to a very sharp sell off in the bond market for one of the bankrupt developed nations. The problem with debt markets, which can be seen in the case of Lehman Brothers below, is that while stocks tend to track down in a linear fashion, bonds are more likely to collapse overnight. Investors believe up to the very last minute that they have most of their value, until they don't.

Commodities prices have not received the benefit of this freshly printed money. Since 2011, the major commodities have fallen in an almost steady trajectory. They have become the most hated asset class on the planet (considered by many to be in a new secular bear market).
The following shows the steady decline of the major metals since 2011:

The next chart shows the entire commodities index since the secular bull market began in 2000. There was a cyclical rise into 2011 and a steady and relentless decline since that peak. Hedge funds have slowly off loaded their commodity positions and many commodity based funds have even shut their doors over the past few weeks.

A secular bull market usually moves through five waves during its completion. This is called the Elliott Wave cycle. The second and fourth waves of the cycle are correction (downward waves). We experienced wave one up from 2000 to 2008, corrected into early 2009 (wave two), then experienced the second wave up (wave 3) into 2011. We have been in the second corrective wave down (wave 4) since .

How low will this wave go before it completes? Based on the chart above it could fall much further. However, as just discussed, pessimism within the sector has reached incredible levels. I like to buy assets that I believe are in secular bull markets when they have declined in price and sentiment is low. This usually causes me to begin buying before a bottom is in place.
New money created by the central banks around the world has flooded into paper assets. If some of that money were to rotate into commodities it would put the bottom in on the current cyclical move downward.
This brings us back to what could potentially slow the QE purchases globally. If commodity prices begin to rise it creates inflation in assets that people use during a day to day basis (unlike the inflation seen in the paper financial markets thus far during the global QE experiment). If real inflation rises (gasoline, food, utilities, health care, or the goods purchased at the store), investors will demand a greater return on their money to compensate for inflation risks. This will cause yields to rise, and it will reveal the true corner that the Federal Reserve and other central banks have painted themselves into.

This process will bring about the endgame of the debt super cycle. A new monetary system is put in place about every 40 years and the current one began in 1971. We are overdue for what has occurred naturally throughout history. This will not bring about the end of the world, it will just bring change. Those that understand it is coming will take advantage of the short term chaos and purchase assets at inexpensive prices (the paper and real estate assets currently back at bubble prices).
For more on the corner the Fed has painted itself into see: The Coming End To The Fed's Illusion

h/t MISH, Short Side Of Long, ZH
Saturday, October 19, 2013
Lacy Hunt: Fed Policy Failures Are Mounting

Federal Reserve Policy Failures Are Mounting
The Fed's capabilities to engineer changes in economic growth and inflation are asymmetric. It has been historically documented that central bank tools are well suited to fight excess demand and rampant inflation; the Fed showed great resolve in containing the fast price increases in the aftermath of World Wars I and II and the Korean War. In the late 1970s and early 1980s, rampant inflation was again brought under control by a determined and persistent Federal Reserve.However, when an economy is excessively over-indebted and disinflationary factors force central banks to cut overnight interest rates to as close to zero as possible, central bank policy is powerless to further move inflation or growth metrics. The periods between 1927 and 1939 in the U.S. (and elsewhere), and from 1989 to the present in Japan, are clear examples of the impotence of central bank policy actions during periods of over-indebtedness.
Four considerations suggest the Fed will continue to be unsuccessful in engineering increasing growth and higher inflation with their continuation of the current program of Large Scale Asset Purchases (LSAP):
- First, the Fed's forecasts have consistently been too optimistic, which indicates that their knowledge of how LSAP operates is flawed. LSAP obviously is not working in the way they had hoped, and they are unable to make needed course corrections.
- Second, debt levels in the U.S. are so excessive that monetary policy's traditional transmission mechanism is broken.
- Third, recent scholarly studies, all employing different rigorous analytical methods, indicate LSAP is ineffective.
- Fourth, the velocity of money has slumped, and that trend will continue—which deprives the Fed of the ability to have a measurable influence on aggregate economic activity and is an alternative way of confirming the validity of the aforementioned academic studies.
If the Fed were consistently getting the economy right, then we could conclude that their understanding of current economic conditions is sound. However, if they regularly err, then it is valid to argue that they are misunderstanding the way their actions affect the economy.
During the current expansion, the Fed's forecasts for real GDP and inflation have been consistently above the actual numbers. Late last year, the midpoint of the Fed's central tendency forecast projected an increase in real GDP of 2.7% for 2013—the way it looks now, this estimate could miss the mark by nearly 50%.
One possible reason why the Fed have consistently erred on the high side in their growth forecasts is that they assume higher stock prices will lead to higher spending via the so-called wealth effect. The Fed's ad hoc analysis on this subject has been wrong and is in conflict with econometric studies. The studies suggest that when wealth rises or falls, consumer spending does not generally respond, or if it does respond, it does so feebly. During the run-up of stock and home prices over the past three years, the year-over-year growth in consumer spending has actually slowed sharply from over 5% in early 2011 to just 2.9% in the four quarters ending Q2.
Reliance on the wealth effect played a major role in the Fed's poor economic forecasts. LSAP has not been able to spur growth and achieve the Fed's forecasts to date, and it certainly undermines the Fed's continued assurances that this time will truly be different.
2. US debt is so high that Fed policies cannot gain traction
Another impediment to LSAP's success is the Fed's failure to consider that excessive debt levels block the main channel of monetary influence on economic activity. Scholarly studies published in the past three years document that economic growth slows when public and private debt exceeds 260% to 275% of GDP. In the U.S., from 1870 until the late 1990s, real GDP grew by 3.7% per year. It was during 2000 that total debt breached the 260% level. Since 2000, growth has averaged a much slower 1.8% per year.
Once total debt moved into this counterproductive zone, other far-reaching and unintended consequences became evident. The standard of living, as measured by real median household income, began to stagnate and now stands at the lowest point since 1995. Additionally, since the start of the current economic expansion, real median household income has fallen 4.3%, which is totally unprecedented. Moreover, both the wealth and income divides in the U.S. have seriously worsened.
Over-indebtedness is the primary reason for slower growth, and unfortunately, so far the Fed's activities have had nothing but negative, unintended consequences.
3. Academic studies indicate the Fed's efforts are ineffectual
Another piece of evidence that points toward monetary ineffectiveness is the academic research indicating that LSAP is a losing proposition. The United States now has had five years to evaluate the efficacy of LSAP, during which time the Fed's balance sheet has increased a record fourfold.
It is undeniable that the Fed has conducted an all-out effort to restore normal economic conditions. However, while monetary policy works with a lag, the LSAP has been in place since 2008 with no measurable benefit. This lapse of time is now far greater than even the longest of the lags measured in the extensive body of scholarly work regarding monetary policy.
Three different studies by respected academicians have independently concluded that indeed these efforts have failed. These studies, employing various approaches, have demonstrated that LSAP cannot shift the Aggregate Demand (AD) Curve. The AD curve intersects the Aggregate Supply Curve to determine the aggregate price level and real GDP and thus nominal GDP. The AD curve is not responding to monetary actions, therefore the price level and real GDP, and thus nominal GDP, are stuck—making the actions of the Fed irrelevant.
The papers I am talking about were presented at the Jackson Hole Monetary Conference in August 2013. The first is by Robert E. Hall, one of the world's leading econometricians and a member of the prestigious NBER Cycle Dating Committee. He wrote, "The combination of low investment and low consumption resulted in an extraordinary decline in output demand, which called for a markedly negative real interest rate, one unattainable because the zero lower bound on the nominal interest rate coupled with low inflation put a lower bound on the real rate at only a slightly negative level."
Dr. Hall also wrote the following about the large increase in reserves to finance quantitative easing: "An expansion of reserves contracts the economy." In other words, not only have the Fed not improved matters, they have actually made economic conditions worse with their experiments. Additionally, Dr. Hall presented evidence that forward guidance and GDP targeting both have serious problems and that central bankers should focus on requiring more capital at banks and more rigorous stress testing.
The next paper is by Hyun Song Shin, another outstanding monetary theorist and econometrician and holder of an endowed chair at Princeton University. He looked at the weighted-average effective one-year rate for loans with moderate risk at all commercial banks, the effective Fed Funds rate, and the spread between the two in order to evaluate Dr. Hall's study. He also evaluated comparable figures in Europe. In both the U.S. and Europe these spreads increased, supporting Hall's analysis.
Dr. Shin also examined quantities such as total credit to U.S. non-financial businesses. He found that lending to non-corporate businesses, which rely on the banks, has been essentially stagnant. Dr. Shin states, "The trouble is that job creation is done most by new businesses, which tend to be small." Thus, he found "disturbing implications for the effectiveness of central bank asset purchases" and supported Hall's conclusions.
Dr. Shin argued that we should not forget how we got into this mess in the first place when he wrote, "Things were not right in the financial system before the crisis, leverage was too high, and the banking sector had become too large." For us, this insight is highly relevant since aggregate debt levels relative to GDP are greater now than in 2007. Dr. Shin, like Dr. Hall, expressed extreme doubts that forward guidance was effective in bringing down longer-term interest rates.
The last paper is by Arvind Krishnamurthy of Northwestern University and Annette Vissing-Jorgensen of the University of California, Berkeley. They uncovered evidence that the Fed's LSAP program had little "portfolio balance" impact on other interest rates and was not macro-stimulus. A limited benefit did result from mortgage-backed securities purchases due to the announcement effects, but even this small plus may be erased once the still unknown exit costs are included.
Drs. Krishnamurthy and Vissing-Jorgensen also criticized the Fed for not having a clear policy rule or strategy for asset purchases. They argued that the absence of concrete guidance as to the goal of asset purchases, which has been vaguely defined as aimed toward substantial improvement in the outlook for the labor market, neutralizes their impact and complicates an eventual exit. Further, they wrote, "Without such a framework, investors do not know the conditions under which (asset buys) will occur or be unwound." For Krishnamurthy and Vissing-Jorgensen, this "undercuts the efficacy of policy targeted at long-term asset values."
4. The velocity of money—outside the Fed's control
The last problem the Fed faces in their LSAP program is their inability to control the velocity of money. The AD curve is planned expenditures for nominal GDP. Nominal GDP is equal to the velocity of money (V) multiplied by the stock of money (M), thus GDP = M x V. This is Irving Fisher's equation of exchange, one of the important pillars of macroeconomics.
V peaked in 1997, as private and public debt were quickly approaching the nonproductive zone. Since then it has plunged. The level of velocity in the second quarter is at its lowest level in six decades. By allowing high debt levels to accumulate from the 1990s until 2007, the Fed laid the foundation for rendering monetary policy ineffectual. Thus, Fisher was correct when he argued in 1933 that declining velocity would be a symptom of extreme indebtedness just as much as weak aggregate demand.
Fisher was able to make this connection because he understood Eugen von Böhm-Bawerk's brilliant insight that debt is future consumption denied. Also, we have the benefit of Hyman Minsky's observation that debt must be able to generate an income stream to repay principal and interest, thereby explaining that there is such a thing as good (productive) debt as opposed to bad (non-productive) debt. Therefore, the decline in money velocity when there are very high levels of debt to GDP should not be surprising. Moreover, as debt increases, so does the risk that it will be unable to generate the income stream required to pay principal and interest.
Perhaps well intended, but ill advised
The Fed's relentless buying of massive amounts of securities has produced no positive economic developments, but has had significant negative, unintended consequences.
For example, banks have a limited amount of capital with which to take risks with their portfolio. With this capital, they have two broad options: First, they can confine their portfolio to their historical lower-risk role of commercial banking operations—the making of loans and standard investments. With interest rates at extremely low levels, however, the profit potential from such endeavors is minimal.
Second, they can allocate resources to their proprietary trading desks to engage in leveraged financial or commodity market speculation. By their very nature, these activities are potentially far more profitable but also much riskier. Therefore, when money is allocated to the riskier alternative in the face of limited bank capital, less money is available for traditional lending. This deprives the economy of the funds needed for economic growth, even though the banks may be able to temporarily improve their earnings by aggressive risk taking.
Perversely, confirming the point made by Dr. Hall, a rise in stock prices generated by excess reserves may sap, rather than supply, funds needed for economic growth.
Incriminating evidence: the money multiplier
It is difficult to determine for sure whether funds are being sapped, but one visible piece of evidence confirms that this is the case: the unprecedented downward trend in the money multiplier.
The money multiplier is the link between the monetary base (high-powered money) and the money supply (M2); it is calculated by dividing the base into M2. Today the monetary base is $3.5 trillion, and M2 stands at $10.8 trillion. The money multiplier is 3.1. In 2008, prior to the Fed's massive expansion of the monetary base, the money multiplier stood at 9.3, meaning that $1 of base supported $9.30 of M2.
If reserves created by LSAP were spreading throughout the economy in the traditional manner, the money multiplier should be more stable. However, if those reserves were essentially funding speculative activity, the money would remain with the large banks and the money multiplier would fall. This is the current condition.
The September 2013 level of 3.1 is the lowest in the entire 100-year history of the Federal Reserve. Until the last five years, the money multiplier never dropped below the old historical low of 4.5 reached in late 1940. Thus, LSAP may have produced the unintended consequence of actually reducing economic growth.
Stock market investors benefited, but this did not carry through to the broader economy. The net result is that LSAP worsened the gap between high- and low-income households. When policy makers try untested theories, risks are almost impossible to anticipate.
The near-term outlook
Economic growth should be very poor in the final months of 2013. Growth is unlikely to exceed 1%—that is even less than the already anemic 1.6% rate of growth in the past four quarters.
Marked improvement in 2014 is also questionable. Nominal interest rates have increased this year, and real yields have risen even more sharply because the inflation rate has dropped significantly. Due to the recognition and implementation lags, only half of the 2013 tax increase of $275 billion will have been registered by the end of the year, with the remaining impact to come in 2014 and 2015.
Additionally, parts of this year's tax increase could carry a negative multiplier of two to three. Currently, many of the taxes and other cost burdens of the Affordable Care Act are in the process of being shifted from corporations and profitable small businesses to households, thus serving as a de facto tax increase. In such conditions, the broadest measures of inflation, which are barely exceeding 1%, should weaken further. Since LSAP does not constitute macro-stimulus, its continuation is equally meaningless. Therefore, the decision of the Fed not to taper makes no difference for the outlook for economic growth.
***
Dr. Lacy Hunt, executive VP of Hoisington Investment Management Company, is an internationally known economist. Before his position at HIMCO, he served as senior economist for the Federal Reserve in Dallas, and as chief US economist for HSBC Group.
Dr. Hunt was one of the blue-ribbon speakers at the just-concluded Casey Research Summit in Tucson, AZ, and his presentation was voted to be "the scariest speech" of the Summit by many attendees. However, Dr. Hunt was only one of the many experts—among them James Rickards, Bud Conrad, and Chris Martenson—who warned of the dire consequences of the Fed's prolonged manipulation of the US economy. Listen to the entire Summit, including timely investment advice and specific stock picks, in the comfort of your home. More here…
Thursday, October 17, 2013

Friday, October 11, 2013

Thursday, October 10, 2013
...But Wall St Is Hearing None of That
The financial markets today are focused on a meeting that Obama and House GOP leadership have a meeting scheduled that is likely to bring another kicking of the debt can, at best. The Dow was up more than 200 points a few minutes ago. The bond market is expecting a six week can kick.

Jobless Claims Spike to Highest In Months
Weekly jobless claims spiked to the highest levels since March this morning.
from the WSJ:

Global PC Sales Plunge 8.6%
from Gartner:
Worldwide PC shipments totaled 80.3 million units in the third
quarter of 2013, an 8.6 percent decline from the same period last year,
according to preliminary results by Gartner, Inc. This marks the sixth
consecutive quarter of declining worldwide shipments.
"The third quarter is often referred to as the 'back-to-school'
quarter for PC sales, and sales this quarter dropped to their lowest
volume since 2008," said Mikako Kitagawa, principal analyst at Gartner.
"Consumers' shift from PCs to tablets for daily content consumption
continued to decrease the installed base of PCs both in mature as well
as in emerging markets. A greater availability of inexpensive Android
tablets attracted first-time consumers in emerging markets, and as
supplementary devices in mature markets."
But Wall St is oblivious. The focus today is on a meeting between Obama and the House GOP leadership that may resolve the budget and debt impasse. The Dow was up 200+ points a few minutes ago.
Wednesday, October 9, 2013
Stocks Goosed Higher Despite Ongoing Budget/Debt Impasse


Obama's Gives Yellen the Nod As Fed Chair
from the WSJ:

Monday, October 7, 2013
Will There Be Treasuries Issued Next Week?
Treasury bills have maturities of anywhere from a few days to 52 weeks. Treasury notes have maturities of between two years and ten years. Treasury bonds have maturities of 30 years. And the Treasury also sells Treasury-Inflation Protected Securites (TIPS), which have terms of 5, 10 or 30 years.
Cotton Prices Crushed As Storm Weakens
via Reuters in Mumbai, India:
Oct 7 (Reuters) - Cotton futures in India, the
world's second-largest grower, are expected to fall this week on
hopes of higher output as rains lead to better yields and due to
approaching supplies from the new season harvest amid sluggish
exports.
by Reuters US:
* Dissipating Tropical Storm leaves cotton crops unscathed
* Fiber sinks to one-month low, extends losses on sell stops
* Global stocks slide as investors remain jittery over U.S.
gov't shutdown
* USDA will not release World Agricultural Supply and Demand
Estimates report on Friday
NEW YORK, Oct 7 (Reuters) - ICE cotton sank on Monday to
post its biggest loss in over six weeks as the weakening of
Tropical Storm Karen eased worry over crop damage in the United
States, the world's top exporter, and as the U.S. government
shutdown and budget impasse kept investors skittish.

Cocoa Continues to Rise Due to Global Long-Term Supply Pressures
Money managers raised bullish bets on cocoa traded in London to a record as global shortages loom for the 2013-14 season that started this month, according to data from NYSE Liffe, the derivatives arm of NYSE Euronext.
Investors were net-long, or betting on higher prices, by 64,759 futures and options in the week ended Oct. 1, the Commitments of Traders report on the exchange’s website showed today. That was the largest bullish bet since publishing of trader holdings began in 2011 and compared with the previous record of 63,419 contracts in the week ended Sept. 24. The beans for December delivery fell 0.5 percent in the latest week.
from the Business Recorder of Pakistan:
NEW YORK: ICE cocoa climbed to a more than one-year high and London futures rallied to the highest in about two years on Monday as the International Cocoa Organization forecast a deficit in the next four years and as recent rains stoked worry of supply concerns in West Africa, the world's top growing region.
by the Public Ledger of Agra.net:
Cocoa futures closed significantly higher on Monday, underpinned by reports that global demand will outstrip supply, industry watchers said.
According to the International Cocoa Organization (ICCO), the global cocoa deficit will be 69,000-70,000 metric tonnes in 2013/14, up from 52,000 tonnes in 2012/13.

Corn Leaps Due to Storm Risk
Wheat and corn futures rose Monday after storms in the Midwest over the weekend threatened both crops.
Wheat for December delivery rose 7.75 cents to $6.9475 a bushel and December corn rose 6 cents to $4.4925 a bushel.
Weekend
storms delayed the harvest of the corn crop and also caused delays in
planting the winter wheat crop, said Todd Hultman, a grain analyst with
DTN/The Progressive Farmer in Omaha, Neb.

Stocks Sink Into the Close
News that a major broker doubled stock futures margins, along with the pressure of the continuing budget impasse in Washington, sank stock markets in the last hour of trading today, with the Dow closing down 136 points.
This was somewhat surprising, given that stocks had rallied out of the starting gate from deep losses, cutting those losses in half by mid-day.

Budget Impasse Doesn't Worry Wall St
Dow opened down more than 130 points, but is rallying sharply at the open. The continuing budget impasse doesn't appear to worry Wall St.


Subscribe to:
Posts (Atom)