Tuesday, June 14, 2011
Stocks Spike Higher Still on Retail Sales, PPI Data
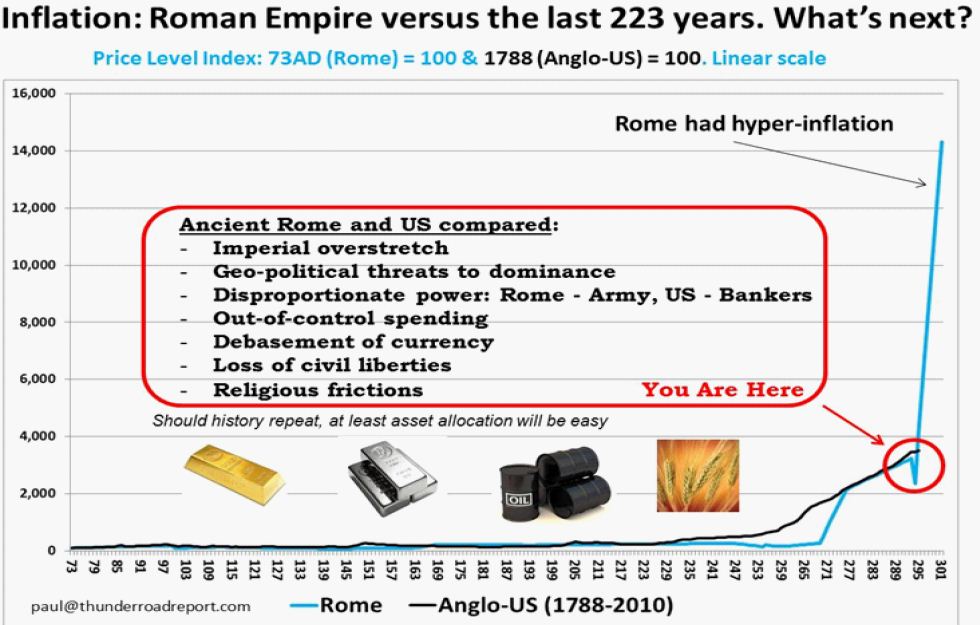
US May PPI came in at 0.2% sequentially, on expectations of 0.1%, and down from 0.8% previously. This was the 11th consecutive increase in PPI. The 12 month change in PPI came at a multi year high 7.3%, much higher than the 6.8% expected, which supposedly is a good thing: inflation is back. PPI ex food and energy was in ling with expectations at 2.1%. Elsewhere, the May Advance Monthly Sales came at -0.2%, on expectations of -0.5%, down from a lower revised 0.3%. Retail sales ex auto and gas came at 0.3% on expectations of 0.2%, with the previous revised lower to 0.2% from 0.3%. Stocks appear to enjoy the increasing inflation on declining economic output.
Monday, June 13, 2011
Big Bounce
Economy Summarized
Excellent economic assessment and summary courtesy of David Rosenberg and Zero Hedge:
David Rosenberg provides the key bulletized market observations that have marked the broad capital markets over the past few months.
- $950 billion of paper equity wealth has been wiped off the map in the past six weeks.
- The Dow is below 12,000 for the first time since March 18th.
- The Transports are down more than 8% from the nearby highs and are down for the year as well
- The Transports/Utilities ratio has broken down to its lowest level since November 9th of last year.
- The Nasdaq is now down for the year (-0.3%)
- The Russell 2000 index is also down for the year (-0.5%).
- The S&P 500 is just 1.1% away from seeing the same fate.
- The S&P 500 has declined in each of the past six weeks, the longest losing streak since June-July 2008.
- The S&P 500 has fallen below its 150-day moving average after breaking below the 50-day and 100-day trendlines earlier in this corrective phase; the 200-day is the next level of support.
- For the Dow, this is the longest string of weekly declines since the Fall of 2002.
- The total six-week decline in the broad market is nearly 7% ... a slow bleed.
- Junk bond spreads widened 25 basis points last week, more evidence of risk re-rating.
- Investment-grade bond spreads widened out 14bps and new issue activity ($0.63 billion) was the lowest of the year.
- Bank of America is back to being a $10 stock after a two week 8% slide — how do the bulls dismiss this out of hand? It's the biggest consumer bank in the country.
- In the past six weeks, Energy, Industrials, Materials, Financials and Consumer Discretionary have all rolled over significantly. The defensives have outperformed dramatically — Healthcare, Utilities, Telecom, and Consumer Staples.
And here is what Rosie believes is ailing the market. Nothing really new here:
- The economy is cooling off and there is no policy stimulus in the pipeline. Ben Bernanke did give a sombre assessment of the economy last August in Jackson Hole but at the same time threw Mr. Market a bone by hinting at a new round of liquidity expansion. Last week, the Fed Chairman delivered an even more sobering outlook and did not offer any olive branch this time around.
- So here we have it economic deceleration but with no policy response. NY Fed President Bill Dudley also gave a speech that was very similar in tone to Bernanke — maybe even more cautious, and while repeating the refrain about second-half recovery prospects he listed an array of downside risks to that forecast. He, Bernanke and Yellen ('The Big Three') would love to do another round of QE (Yellen also gave a speech on Friday on housing) but the bottom line is that they are gun-shy after receiving so many complaints from foreign governments, Congress, Wall Street and Fed Bank Presidents that they just do not have the political capital to engage in more stimulus (though it will come at some point but maybe at a similar strike price as last August; dare we say, 1,040 on the S&P 500).
- While the economists have cut their numbers, the equity analysts have yet to do that with their earnings numbers. That comes next.
- Leading indicators are suggesting that we are in more than just a "soft patch" — the jargon of Wall Street economists. The ECRI leading economic index has fallen now for four weeks in a row!
- Global cooling. The Chinese economy is also slowing down with auto sales declining now for two months in a row and the PM! perilously close to the 50 level. Retail sales in Brazil fell 0.2% in April, the first decline in a year and the news came on top of a sudden sharp slowing in industrial output. U.K. factory output fell 1.7% in April as well and France posted a surprising 0.3% drop in industrial production.
- Tightening monetary policies to combat rising inflation pressure across the emerging market world.
- The situation in Europe is untenable — Germany's finance minister is drawing a line in the sand and calling for some sort of Greek restructuring in which bond holders will also have to take a haircut. This has caused the ECB's Trichet to almost go apoplectic. Of course, the ECB is holding onto hundreds of billions of dollars of P.I.G.S. debt on its balance sheet so any haircut would render the central bank insolvent in its own right.
- Threatening not to repo restructured debt is like saying to the Greek banking industry to kiss itself goodbye (a likely prelude to Greece exiting the eurozone, by the way). But Trichet is not elected, the likes of Angela Merkel and Wolfgang Schauble (the finance minister in question here who came right out and said a Greek restructuring is "inevitable") just happen to be, and it looks like the German taxpayer-funded bailouts are coming to an end. See Rift Over Greece Deepens in Europe on page B1 of the weekend WSJ. Some markets are starting to price in the inevitability of sovereign debt defaults in Europe, with 5-year credit default swaps soaring to record highs in Greece, Ireland and Portugal.
- One can't help but think that the ECB rate hike (and the threat to do more!) will go down as a colossal mistake the same central bank made in the summer of 2008. Considering that most of Spain's mortgage market is variable-term and the housing market is beset with tremendous excess supply and downward price potential, the ECB rate hike is like a stake in the heart — to combat perceived inflationary pressures in Germany.
- The slide in U.S. bond yields is telling you that an economic slowdown is here and here to stay beyond Q2, despite consensus views to the contrary. The fact that copper was down in the same week that oil was up says two things here — the former reflects the falloff in Chinese imports; the latter tells you a thing or two about just how thinly balanced the global demand-supply for crude is given that the move back to $120/bbl was all due to discord within OPEC in terms of whether or not to bump production up (looks like the Saudis will be going it alone).
- Actually, it is all about discord here — within OPEC, Congress and the White House (see the editorial piece The Economy and Washington on page 8 of the Sunday NYT 'Week in Review' section), the confines of the Fed, the ECB and Germany, etc. Discord, instead of decision-making, in the current environment is not a good thing— leaving the financial markets in a heightened state of uncertainty.
Stocks Collapse In Sell-Off
Friday, June 10, 2011
Thursday, June 9, 2011
Highest Price for Corn in Three Years
Bad News for Anyone Who Eats
from Zero Hedge regarding this morning's USDA update:
So much for transitory inflation as corn prices are again pennies of a fresh all time high. Earlier today an update by the USDA showed that corn stocks will come in much lower than expected at the end of the 2011/12 marketing year at just 695 million bushels: this is far lower than the analysts consensus of 771 million bushels. The spring weather was blamed for the drop: "cold, rainy spring and flooding cut U.S. corn plantings by 1.6 percent, will reduce the harvest by 2 percent and will keep U.S. corn supplies at their tightest level in 15 years through the fall of 2012, the government said on Thursday." Another factor for the record price: surging China demand: "USDA also forecast a hefty increase in corn use by China -- up 8 million tonnes, or 5 percent, this year and up 13 million tonnes, or 8 percent, in 2011/12. China will draw down its stocks rather than import corn, USDA said." Just like in China where record droughts have been replaced with deadly floods, the weather continues to be unusually volatile, not just in the US: "Besides plaguing the eastern Corn Belt, rains and floods have slashed the rice crop by 5.5 percent since May, USDA said. Drought in the Southwest would reduce the cotton crop by 1 million bales, or nearly 6 percent, to 17 million bales, and the rice crop, at 199.5 million hundredweight, would be the smallest in four years." This is probably the latest data the market needed to completely ignore today's worse than expected initial claims data, and go into full "Inflation: ON" mode. In other news, expect Obama to announce the launch of an Adverse Weather Task Force investigating speculative movements in air masses momentarily.
Jim Rogers: Worse Crisis Coming Because of Debt
Legendary investor Jim Rogers, CEO of Rogers Holdings, offered a very glum outlook on the U.S. economy yesterday. According to him, we’re headed for a crisis worse than 2008, the Chinese Yuan will soon be safer than the dollar, and Fed Chairman Ben Bernanke will probably institute another round of money-printing, or QE3.
“The debts that are in this country are skyrocketing,” he told CNBC. “In the last three years the government has spent staggering amounts of money and the Federal Reserve is taking on staggering amounts of debt.
“When the problems arise next time…what are they going to do? They can’t quadruple the debt again. They cannot print that much more money. It’s gonna be worse the next time around.”
He later added, “The U.S. is the largest debtor nation in the history of the world. The debts are going through the roof. Would you keep lending money to somebody who’s spending money and not doing anything about it? No you wouldn’t.”
Because of that, he said the Chinese Yuan will be a safer currency bet than the dollar. And what may even better is gold and silver: he’s hoping the price goes down on both so he can “pick up the phone and buy more.”
He’s also convinced Ben Bernanke, who he calls a “disaster,” will institute another round of quantitative easing, essentially printing money, later this year.
“They’re gonna bring it back because [Bernanke will] be terrified and Washington will be terrified,” he said. “There’s an election coming in November 2012. Washington’s gonna print more money.”
According to him “draconian” cuts will be needed to control U.S. debt:
Tuesday, June 7, 2011
Stocks Go Negative In Closing Minutes of Session
from WSJ:
NEW YORK—A gloomy economic assessment from Federal Reserve Chairman Ben Bernanke erased an earlier stock rally, sending major indexes in the final minutes of Tuesday's session to their fifth consecutive drop...
The sharp reversal came after Bernanke offered downbeat comments on the U.S. economy. He said economic growth has been "somewhat slower" than expected, although he added that the recovery should pick back up in the second half of 2011 despite recent signs of weakness.
Mr. Bernanke also said the recovery two years after the end of the recession remains "uneven" and that conditions—particularly in the labor market—remain troubled.
"The market is not buying what Bernanke is selling," said Keith Bliss, senior vice president at Cuttone & Co., a brokerage on the New York Stock Exchange floor. "He's not wowing the crowd."
Mr. Bernanke's comments follow a drumbeat of weak economic data and worries that the recovery is running out of steam. The government's disappointing jobs report last week came on the heels of several weak regional manufacturing reports and consumer-confidence data that have fueled anxiety on Wall Street.
"[Bernanke] certainly seemed to be a little more dour on the economy," said Jay Suskind, senior vice president at Duncan-Williams. "If you had to classify it, it's more glass half empty than glass half full."
The disappointing data, combined with the looming end of the Fed's bond-buying program, or "quantitative easing," has weighed on investor sentiment. Chatter on a third round of quantitative easing, or "QE3," has intensified in recent weeks as more investors are discussing whether the Fed may have to enact some new form of monetary support.
Stocks Lose All Gains
Monday, June 6, 2011
Chronic Unemployment Now Worse Than Great Depression
CBS News correspondent Ben Tracy reports that the chronically unemployed face the hardest road back to recovery, and that while the jobs picture may be improving statistically on a national level, it is not for them...
About 6.2 million Americans, 45.1 percent of all unemployed workers in this country, have been jobless for more than six months - a higher percentage than during the Great Depression.
Hussman: Deterioration of Economic Fundamentals
Friday, June 3, 2011
Unemployment Rises to 9.1%, Money Mayhem Following Massive NFP Disappointment
Massive collapse in the American employment situation: May NFP at 54K, down from 244K, and not only below consensus of 165K, but below the lowest economist prediction of 65K. Private payrolls increased just 83K on expectations of 170K. Manufacturing payroll dropped 5K on expectations of a 10K rise. The unemployment rate was 9.1%, although U-6 declined from 15.9% t 15.8%. The absolute number of unemployed increased fom 13.747 million to 13.914 million. For the third month in a row the Labor Force Participation rate remained flat at 64.2%.
and as if that isn't bad enough, also from ZH:
Take away the Birth/Death adjustment of 206,000 and the Real NFP is: -150,000. This is the biggest monthly B/D adjustment in over a year. And if as all the pundit claimed last month, demanding the McDonalds addition of 62,000 janitorial, part-time jobs be added to the May number, the economy really lost over 200,000 in May.
The household survey must have been atrocious!
Thursday, June 2, 2011
Fed Not to Begin QE3 for Now
by John Hilsenrath at WSJ:
Federal Reserve officials are in no hurry to respond to recent indications U.S. economic growth has hit another soft patch, despite chatter in financial markets that the Fed might start a new program of U.S. Treasury-bond purchases to boost growth.
The central bank has already purchased more than $2 trillion of mortgage and Treasury bonds. The purchases are meant to hold interest rates down by reducing the supply of securities in private hands and to drive investors into areas such as stocks to encourage businesses and consumers.
Fed Chairman Ben Bernanke signaled in April that the hurdle to more "quantitative easing," as it is known, is very high and Fed officials have done nothing to indicate that Mr. Bernanke's guidance has changed as economic data has worsened in recent weeks.
In an April news conference, Mr. Bernanke said the tradeoffs that would come with additional purchases were becoming unappealing. "It's not clear we can get substantial improvements in [employment] without some additional inflation risk," he said.
Fed officials have largely held to that line. In comments last week, St. Louis Fed president James Bullard said the Fed was entering a period in which Fed policy will be on pause—meaning it won't be trying to push interest rates either higher or lower. Charles Evans, president of the Chicago Fed and a strong advocate of past programs, said earlier last month that what the Fed had done already was "sufficient."
In comments Wednesday, Cleveland Fed president Sandra Pianalto said the Fed's current stance was appropriate and added the recovery was likely to continue, even though growth "may be frustratingly slow at times."
Mr. Bernanke has argued that past bond purchases haveworked, but it has have taken a political toll on the Fed. Critics in Congress and overseas say the Fed is fueling inflation globally.
"They don't want to do QE3," said Vincent Reinhart, an economist who formerly ran the Fed's influential division of monetary affairs. QE3 is what many traders have dubbed the possibility of a third round of Fed securities purchases.The last round of quantitative easing, which will amount to $600 billion of bond purchases, is set to conclude at the end of June.
A boost from Congress, through additional deficit spending, looks equally unlikely. Republicans have crafted an agenda based on spending cuts and would likely be reluctant to embrace new efforts to stimulate growth through fiscal policy. New tax cuts would also face a tough reception, given Washington's currentfocus on reducing the long-run deficit.
The Obama administration wants more infrastructure spending in the near term, but administration officials, stung by the divisive legacy of the 2009 stimulus bill, don't call it stimulus.
Infrastructure spending, in addition to education and research and development programs already proposed by Mr. Obama, are "policies that have the potential to impact job creation now but also have the ability to increase our competitiveness," said Brian Deese, deputy director of the National Economic Council.
The current mindset could change if the economy deteriorates. Mr. Bernanke has indicated that the outlook for inflation will play a key role in his decisions about monetary policy. Rising inflation could force the Fed to raise interest rates. A declining rate of inflation could force it to consider startinga new easing program.
The Fed initiated its last program of quantitative easing in 2010 amid worries that the U.S. was slipping toward deflation, or falling consumer prices. The behavior of bond markets doesn't indicate that deflation is a serious worry right now. Prices of Treasury Inflation Protected Securities, also known as TIPS, indicate that investors expect 2.8% inflation in five years, substantially more than was the case last August when the Fed started talking about a new round of quantitative easing. Back then, expected inflation was on a downward trajectory, from 2.8% to less than 2.2% in a couple of months.
Measured inflation is also higher than it was last year. When the Fed initiated the program in November, consumer prices were up 1.1% from a year earlier, well below the Fed's 2% goal. In April they were up 3.1% from a year earlier.
"We don't think it's likely at all, but things could change," Michael Pond, a bond strategist at Barclays Capital, said of the chances of another round of easing. "If growth slows well below its trend and on top of that you have inflation and inflation expectations coming down, it is certainly possible. At this point it is not on the table."
Wednesday, June 1, 2011
June Swoon
Killing Crude
"We're on the verge of a great, great depression" --Peter Yastrow, market strategist for Yastrow Origer
from CNBC:
Wall Street is having a hard time figuring out what to do now that the U.S. economy appears to be sputtering and yields are so low, Peter Yastrow, market strategist for Yastrow Origer, told CNBC.
Dow Loses 190 Points
And It Just Gets Worse
Stocks are now down 160 points, wiping out not only yesterday's gains, but most of the gains for the entire week! Look at the slope of that decline!
Australia GDP Slips Too!
from the BBC:
/Australia's/ economy contracted by 1.2% in the first three months of the year, compared with the previous quarter, the latest government figures showed.
The government said flooding and cyclones in resource rich states of Queensland and Western Australia had a significant impact on growth.
Australia's economy is heavily reliant on its resources sector.
May Economic Data Universally Bad
U.S. ISM, just as in UK and China, as indicated in this headline from the Wall Street Journal, has also slowed appreciably. Ignore that, Wall Street! I give them 24 hours to do just that!
from WSJ:
The U.S. manufacturing sector slowed sharply in May, according to data released Wednesday by the Institute for Supply Management...
The ISM's manufacturing purchasing managers' index fell to 53.5 in May from 60.4 in April. Readings above 50 indicate expanding activity.
Economists surveyed by Dow Jones Newswires had expected the May PMI to slip to only 57.0.
from Marketwatch:
A Chicago-area manufacturing gauge dropped by the largest amount in nearly two-and-half years in May, in a further sign that the rise in oil prices and the Japanese earthquake have affected activity.
The Chicago PMI fell to a reading of 56.6% in May, the lowest reading since Nov. 2009, from 67.6% in April.
ADP Plunges, Stocks Follow
"Today’s ADP National Employment Report suggests that employment growth slowed sharply in May. Employment in the nonfarm private-business sector rose 38,000 from April to May on a seasonally adjusted basis. A deceleration in employment, while disappointing, is not entirely surprising. In the first quarter, GDP grew at only a 1.8% rate and only about 2¼% over the last four quarters. This is below most economists’ estimate of the economy’s potential growth rate and normally would be associated with very weak growth of employment."
Not Just Us!
Tuesday, May 31, 2011
Terrible Triple Trifecta!
And now, consumer confidence plunges also. May consumer confidence completed the terrible trifecta of bad news, coming at 60.8 on expectations of 65.4, and down from 66.6.
PMI Collapses, Stocks Follow
from Zero Hedge:
The May Chicago PMI is out and contrary to the herd of clueless Wall Street idiots, better known in polite circles as economists, it came at 56.6 on expectations of 62.0, a collapse drop from the 67.6 before. This is the worst monthly drop since the economy imploded back in October 2008, and the second largest two month drop since 1980! A quick look at the New Orders index indicates it was the lowest since September 2009. But the good news: the economy is still in expansion... for about 1 more month. The release says it all: "NEW ORDERS and PRODUCTION posted their largest declines in several years...but remained positive" and "INVENTORIES accelerated buildup" - thank god for artificial economic expansion. And from the respondents: "Fuel cost are going to have a major impact on business activity in a negative way that will slow recovery to a crawl." Uh, what recovery? Just you wait until QE3 is announced in 3 months. And elsewhere, the May consumer confidence completed the trifecta of bad news, coming at 60.8 on expectations of 65.4, and down from 66.6.
Case Shiller Plumbs New Recession Lows, and Stocks Rise
Monday, May 30, 2011
Taxes on Traders Almost Certain to Go Up
Traders Accounting just sent me this! There are at least FOUR new taxes in this. This will encourage capital flight to overseas. Bad news for the U.S. economy!
from Traders Accounting:
With lawmakers putting an increasing emphasis on the federal budget deficit, Bloomberg reports it is likely those day trading for a living could see a number of tax increase in 2013.
Unless Congress acts, the federal tax cuts extended last year are set to expire at the end of 2012. Once they expire, day traders will see taxes on incomes, capital gains and dividends all rise moving into 2013.
Compounding the issue, those in higher income brackets are also set to deal with higher unearned income taxes in 2013 to pay for the government's health insurance plans.
"The deficit is an issue," Bill Fleming, managing director at New York-based accounting and advisory firm PricewaterhouseCoopers, told the news source. He added many people "have already decided in their minds that something is going to happen and they're going to pay higher taxes."
Bloomberg says the White House has proposed to allow taxes on capital gains and dividends to jump from 15 to 20 percent. In addition, the tax rate for couples earning more than $250,000 or individuals earning more than $200,000 would jump from 35 percent to 39.6 percent.
Last year, a commission set up to brainstorm ways to reduce the deficit proposed dropping the overall income tax rate, but including capital gains taxes and dividends and standard income.
With these ongoing shifts and changes, traders may have trouble keeping up with their tax needs. Experts say some may be better off delegating that work in order to focus more on the heart of the business.
Sunday, May 29, 2011
GDP Fraud
John Mauldin quoted this in his newsletter:
Gaming the GDP Numbers
I know I should quit, but this one quick note, as this just really annoys me. I get the methodology and rationalization of how GDP is calculated, but it does have the appearance of being “gamed.” This from my friends at Consumer Metrics. Link to the full report after.
“The importance of the price deflater used by the BEA cannot be overstated. In calculating the "real" GDP the BEA continued to use an overall 1.9% annualized inflation rate, which is substantially lower than the inflation rates being reported by any of the BEA's sister agencies. The mathematical implications of the deflater are simple: a lower deflater creates a higher ‘real’ GDP reading. If April's CPI-U (as reported by the Bureau of Labor Statistics) of 3.2% year-over-year inflation is used as the deflater, the reported 1.84% annualized growth rate shrinks to a 0.56% annualized rate, and the ‘real final sales of domestic products’ is actually contracting at a 0.63% rate. If instead of the year-over-year CPI-U we were to use the annualized CPI-U from just the first quarter (5.7%), the ‘real’ GDP would be shrinking at a 1.82% annualized rate, and the ‘real final sales of domestic products’ would be contracting at a recession-like 3.01%.” ( http://www.consumerindexes.com/)