Another phenomenal article by Gordon Long:

 The fork in the road which we chose has resulted in:
 What is to stop U.S. banks and their customers from creating $1 trillion, $10 trillion or even $50 trillion on their computer keyboards to buy up all the bonds and stocks in the world, along with all the land and other assets for sale in the hope of making capital gains and pocketing the arbitrage spreads by debt leveraging at less than 1 per cent interest cost? This is the game that is being played today.”


 FLAWED PUBLIC POLICY DECISIONS ASSURE THE OUTCOME


Thursday, October 28, 2010
Debase, Default, and Deny

Dollar in Freefall
"...if indeed the Fed sees the Dollar as one of its key policy levers for preventing inflation from staying below its mandate for a prolonged period – the Dollar needs to fall a lot further from here." --Robin Brook, Goldman Sachs


Stocks Reverse, Go Negative

The Fed polled the primary dealers this morning to know what they want the Fed to do with QE2. Unbelievable. Monetary by poll!

Futures Rise on "Seasonally Adjusted" Jobless Claims

Wednesday, October 27, 2010
Turbulent Day for Stocks
Durable goods was up 3.3%, but only in the transportation sector. Everything else was down 0.8%.
Existing home sales were up 6.6%, a good showing.

But stocks are down for worries over QE2, Fed over-reach, P&G and Whirlpool earnings,
Tuesday, October 26, 2010
What Inflation Looks Like in Real Life
by Jake Weber of the the Casey Report:
The Casey Report provides a useful glance at the real inflation currently ravaging items that are actually purchased by Americans, not those captured by the Fed's BLS statistics: "On average, our basic food costs have increased by an incredible 48% over the last year (measured by wheat, corn, oats, and canola prices). From the price at the pump to heating your stove, energy costs are up 23% on average (heating oil, gasoline, natural gas). A little protein at dinner is now 39% higher (beef and pork), and your morning cup of coffee with a little sugar has risen by 36% since last October." Of course, the ongoing deflation in items purchases requiring leverage will continue to skew the CPI so far south to make all those who bought 5 Year TIPS yesterday at negative yields end up losing money on the transaction.
Chart of the Week: Inflation in the Real World, by Jake Webber of Casey Report
As is often the case, there is a big difference between what the government statistics are reporting and what’s going on in the real world. According to the most recent inflation reading published by the Bureau of Labor Statistics (BLS), consumer prices grew at an annual rate of just 1.1% in August.
The government has an incentive to distort CPI numbers, for reasons such as keeping the cost-of-living adjustment for Social Security payments low. While there’s no question that you may be able to get a good deal on a new car or a flat-screen TV today, how often are you really buying these things? When you look at the real costs of everyday life, prices have risen sharply over the last year. For simplicity’s sake, consider the cash market prices on some basic commodities.

You probably aren’t buying new linens or shopping for copper piping at the hardware store every day, but I included these items to show the inflationary pressures on some other basic materials that will likely affect consumer prices down the road.
The jump in gold and silver prices illustrates that it’s not just supply and demand issues driving the precious metals higher – the decline in purchasing power of the dollar is also showing up in the price of physical goods. It is because stashing wheat and cotton in the garage is an impractical way to protect purchasing power that investors are increasingly looking to protect themselves with the monetary metals – a trend that is now very much in motion.

Broad Commodity Indexes Continue to Rise

The High Price of Rice

Consumer Confidence Beats Expectations, Stocks Surge Temporarily

Case Shiller Contracts in August
“A disappointing report. Home prices broadly declined in August. Seventeen of the 20 cities and both Composites saw a weakening in year-over-year figures, as compared to July, indicating that the housing market continues to bounce along the recent lows,” says David M. Blitzer, Chairman of the Index Committee at Standard & Poor’s. “Over the last four months both the 10- and 20-City Composites show slowing growth, after sustaining consistent gains since their April 2009 troughs.
“The month-over-month growth rates tell the same story. Fifteen of the 20 MSAs and the two Composites saw a decline in the month of August as compared to July levels. The 10- and 20-City Composites fell 0.1% and 0.2%, respectively. Indeed, the housing market appears to have stabilized at new lows. At this time, it does not seem that any of the markets are hanging on to the temporary momentum caused by the homebuyers’ tax credits.”
Monday, October 25, 2010
Here Comes Mortgage Meltdown, Act 2 (part 2)
part 2 from John Mauldin:
At the end of last week's letter on the whole mortgage foreclosure mess, I wrote:
"All those subprime and Alt-A mortgages written in the middle of the last decade? They were packaged and sold in securities. They have had huge losses. But those securities had representations and warranties about what was in them. And guess what, the investment banks may have stretched credibility about those warranties. There is the real probability that the investment banks that sold them are going to have to buy them back. We are talking the potential for multiple hundreds of billions of dollars in losses that will have to be eaten by the large investment banks. We will get into details, but it could create the potential for some banks to have real problems."
Real problems indeed. Seems the Fed, PIMCO, and others are suing Countrywide over this very topic. We will go into detail later in this week's letter, covering the massive fraud involved in the sale of mortgage-backed securities. Frankly, this is scandalous. It is almost too much to contemplate, but I will make an effort.
But first, let me acknowledge the huge deluge of emails I got over last week's letter, the most I can ever remember. I thought about just making this week's letter a response to many of them, but decided I needed to go ahead and finish the topic at hand. Maybe another time. As a side note, I quoted a letter that came to me anonymously via David Kotok. I said if I found out who wrote it, I would give them credit. It was originally written by Gonzalo Liro, at www.gonzalolira.blogspot.com.
Many of you wrote to point out that his argument about the tracking of title was not correct, but others pointed out many other issues as well. This is one of the most complex problems we face, and I got a lot of good information from readers. It just makes me wish I had our new web site finished so you could avail yourselves of the wisdom among my readers. We are close, down to final changes. And now, on to today's letter.
"The delegated flow channel purchased approximately $50 billion of prime mortgages annually. These mortgages were not underwriten by us before they were purchased. My Quality Assurance area was responsible for underwriting a small sample of the files post-purchase to ensure credit quality was maintained.
"These mortgages were sold to Fannie Mae, Freddie Mac [We will come back to this - JM] and other investors. Although we did not underwrite these mortgages, Citi did rep and warrant to the investors that the mortgages were underwritten to Citi credit guidelines.
"In mid-2006 I discovered that over 60% of these mortgages purchased and sold were defective. Because Citi had given reps and warrants to the investors that the mortgages were not defective, the investors could force Citi to repurchase many billions of dollars of these defective assets. This situation represented a large potential risk to the shareholders of Citigroup.
"I started issuing warnings in June of 2006 and attempted to get management to address these critical risk issues. These warnings continued through 2007 and went to all levels of the Consumer Lending Group.
"We continued to purchase and sell to investors even larger volumes of mortgages through 2007. And defective mortgages increased during 2007 to over 80% of production."
Mr. Bowen was no young kid. He had 35 years of experience. He was the guy they hired to pay attention to the risks, and they ignored him. How could a senior manager not get such an email and not notify his boss, if only to protect his own ass? They had to have known what they were selling all the way up and down the ladder. But the music was playing and Chuck Prince said to dance and rake in the profits (and bonuses!). More from his testimony:
"Beginning in 2006 I issued many warnings to management concerning these practices, and specifically objected to the purchase of many identified pools. I believed that these practices exposed Citi to substantial risk of loss.
And now taxpayers own 75% of Citi, and our losses to them are huge. They are going to get worse, as we will see.
Now let's turn to the testimony of Keith Johnson, who worked for various mortgage companies and in 2006 became the president and chief operating officer of Clayton Holdings, the largest residential loan due diligence and securitization surveillance company in the United States and Europe. This is testimony he gave before the Financial Crisis Inquiry Commission. Part of the testimony is by his associate Vicki Beal, senior vice-president of Clayton. The transcript is some 277 pages long, so let me summarize.
Investment banks would come to Clayton and give then roughly 10% of the mortgages that they intended to buy and put into a security. Clayton rated them on whether the documentation was what it was supposed to be, not as to whether they thought it was a good loan. Still, 46% of the loans did not have proper documentation (out of a pool of 9 million loans) and 28% had what was determined to be level 3 disqualifications that simply had no mitigating circumstances. Understand, these were loans that were already written, and there was no effort to check the facts, just the documentation.
And ultimately 11% of these loans (39% of the level 3's) were put back in by the investment bank. And what happened to the loans that were rejected? (This might require an adult beverage and a few expletives deleted.)
"MR. JOHNSON: I think it goes to the 'three strikes, you're out' rule.
"CHAIRMAN ANGELIDES: So this was a case of - okay, three strikes.
"MR. JOHNSON: I've heard that even used. Try it once, try it twice, try it three times, and if you can't get it out, then put -
"CHAIRMAN ANGELIDES: Well, the odds are pretty good if you are sampling 5 to 10 percent that you'll pop through. When you said the good, the bad, the ugly, the ugly will pop through."
Yes, you read that right. If a loan was rejected a second time, it went back into yet another pool for a third try. The odds of coming up three times, when only 5 or 10 percent are sampled? About 1 in a thousand. Popping through, indeed.
Clayton presented their data to the ratings agencies, investment banks, and others in the industry. They were frustrated that no one was really paying attention or taking heed of their warnings.
Here is what Shahien Nasiripour, the business reporter for the Huffington Post, wrote (his emphasis). For those interested, the entire article is worth reading. (http://www.huffingtonpost.com/2010/09/25/wall-street-subprime-crisis_n_739294.html):
"Johnson told the crisis panel that he thought the firm's findings should have been disclosed to investors during this period. He added that he saw one European deal mention it, but nothing else.
"The firm's findings could have been 'material,' Johnson said, using a legal adjective that could determine cause or affect a judgment.
"It's unclear whether the firms ended up buying all of those loans, or whether Wall Street securitized them all and sold them off to investors.
"'Clayton generally does not know which or how many loans the client ultimately purchases,' Beal said. That likely will be the subject of litigation and investigations going forward.
"'This should have a phenomenal effect legally, both in terms of the ability of investors to force put-backs and to sue for fraud,' said Joshua Rosner, managing director at independent research consultancy Graham Fisher & Co.
"'Original buyers of these securities could sue for fraud; distressed investors, who buy assets on the cheap, could force issuers to take back the mortgages and swallow the losses.
"'I don't think people are really thinking about this,' Rosner said. 'This is not just errors and omissions - this appears to be fraud, especially if there is evidence to demonstrate that they went back and used the due diligence reports to justify paying lower prices for the loans, and did not inform the investors of that."
"Beal testified that Clayton's clients use the firm's reports to 'negotiate better prices on pools of loans they are considering for purchase,' among other uses.
"Nearly $1.7 trillion in securities backed by mortgages not guaranteed by the government were sold to investors during those 18 months, according to Inside Mortgage Finance. Wall Street banks sold much of that. At its peak, the amount of outstanding so-called non-agency mortgage securities reached $2.3 trillion in June 2007, according to data compiled by Bloomberg. Less than $1.4 trillion remain as investors refused to buy new issuance and the mortgages underpinning existing securities were either paid off or written off as losses, Bloomberg data show.
"The potential for liability on the part of the issuer 'probably does give an investor more grounds for a lawsuit than they would ordinarily have', Cecala said. 'Generally, to go after an issuer you really have to prove that they knowingly did something wrong. This certainly seems to lend credibility to that argument.'
"'This appears to be a massive fraud perpetrated on the investing public on a scale never before seen,' Rosner added."
Basically, if buyers of 25% or more of a mortgage-backed security can come together, they have standing to sue the mortgage servicer to do its duty to the investors and make putbacks of bad mortgages, and if they fail to do so the plaintiffs can take control of the process and take the issuer to court directly (that's a very simplistic description but roughly accurate).
There are two key take-aways. First, note that a European entity is involved. Hundreds of billions of dollars of this junk was sold to European banks and funds. And these guys get together at conferences (sometimes they even invite me to speak). So Helmut will be talking to Lars who will talk to Jean Pierre and they will realize they all own some of this junk. They will be watching with very real interest to see how the big boys at PIMCO and Black Rock and the New York Fed fare in their efforts. And then you can count on them all piling on (more later on this).
Second, little noticed this week was the fact that The Litigation Daily wrote that Philippe Selendy of Quinn Emanuel Urquhart & Sullivan has been retained by the Federal Housing Finance Agency (FHFA), which oversees Fannie Mae and Freddie Mac, to investigate billions of dollars in potential claims against banks and other issuers of mortgage-backed securities.
Who? Not on your celebrity list? Just wait. He will soon be getting the best tables everywhere. He and his firm are the guys representing MBIA in all their cases against Countrywide and Merrill Lynch. And they are kicking ass. Slowly to be sure, but very steady. That means Fannie and Freddie are getting ready to get serious.
They were sold well over $227 billion of the subprime garbage issued in 2006 and 2007. And the bad stuff started before then. But they have one advantage that the guys at PIMCO, et al. don't have: they (or actually the FHFA) are a federal agency. That means they have subpoena power. The agency has sent 64 subpoenas to issuers of mortgage-backed securities, and although they have not said who they went to, they obviously include almost everyone and clearly all the big players. (They couldn't have ignored Goldman, could they? Naah. Too obvious.)
From American Lawyer.com (I know, this website is probably already on your favorites list, but for those souls who actually have a life I provide the text):
"Through those subpoenas, the agency could gain access to the loan files for the mortgages that backed the securities it bought and thus establish whether the mortgages were what the issuers represented them to be in securities contracts. According to the Journal, the difficulty of obtaining loan files has been a big obstacle for investors trying to force issuers to repurchase bonds.
"If the FHFA were to decide down the road to initiate litigation, it would still have to have the support of a percentage (usually 25 percent) of its fellow bondholders for each issue. But given what the agency and its Quinn lawyers will be able to see before bringing suit, it probably won't be too hard to get other investors on the bandwagon." (http://www.quinnemanuel.com/media/183456/hurricane%20warnings%20fannie%20mae%20and%20freddie%20mac%20hire....pdf)
It is tough not to jump to the conclusion, but we need one more piece of the puzzle before we get there.
Let's look at a report by Branch Hill Capital, a hedge fund out of San Francisco. And before we start on it, let me point out they are short Bank of America. You can see the full PowerPoint at http://www.businessinsider.com/bank-of-america-mortgage-report-2010-10#-1.
(And let me say a big thanks to the author of the report, Manal Mehta, for all the background material he sent me and his help with this week's letter. It helped make it a lot better. Of course, any erroneous conclusions or outrageous statements are all mine.)
First, they point out that the potential size of Bank of America's (BAC) liabilities is $74 billion (with a B). And that is just for Countrywide. That does not include Merrill, which is also large. Against that they have set aside $3.9 billion. You can count on more suits than just the PIMCO, et al. mentioned above.
In the MBIA case, the judge has ruled that the suit can proceed even though BAC has denied responsibility. Although on appeal, this is high-stakes poker. Countrywide originated over $1.4 trillion of mortgages in 2005-2007. MBIA alleges that over 90% of the defaulted or delinquent loans in the Countrywide securitizations show material discrepancies. Care to take the under in the over/under bet on that?
Further to the case on BAC, Merrill was the largest originator of subprime CDOs during the housing boom, for another $120 billion, along with about $255 billion of residential mortgage-backed securities.
And then there are all those CDOs (collaterized debt obligations). Merrill did a lot of those that went sour. This deserves it own leter, but a gentleman named Wing Chau went from making $140k a year to $25 million in just a few years, putting together CDOs from Merrill, some of which were completely bankrupt in just six months.
Countrywide has already settled with the New York pension funds for $624 million, one of the largest securities fraud settlements in US history. And the line is growing longer.
Of course, BAC CEO Brian Moynihan denied this week that there is a problem. Let's look at Moynihan's statements at the last earnings call and compare them to what the judge in the case said earlier. Moynihan:
"... we execute repurchases on a loan by loan basis... And as we learn more, and again, our perspective on this - we're going to be quite diligent as I said in defending the interest of our shareholders. This really gets down to a loan-by-loan determination and we have, we believe, the resources to deploy against that kind of a review."
Back in June the judge on the case (a Judge Bransten) said (from the transcript):
"I think that it makes all the sense in the world that you can use a sample to prove the case because otherwise I can't imagine a jury listening to 386 thousand cases. Even if you have that available, nevertheless you are not going to present that to a jury or even to a judge. I'm patient but not that patient. So therefore it is going to be a sample in the end..."
OK, let me get this straight, Brian. Your company committed fraud, with robosignings and all the rest, and you won't man up and take responsibility? You and your lawyers want to thrash this out, case by case, fighting a trench-warfare, rear-guard action? Well I'm afraid that's not going to work out for you. There are so many examples of Countrywide outright fraud that it is going to be hard to convince a jury that BAC is not on the hook. Will it take years? Of course.
You can read the PowerPoint for details. Bottom line: BAC is probably liable for putbacks that could total over a hundred billion. And that is just BAC.
Think Citi. And any of the scores of mortgage originators and investment banks. There were a couple of trillion dollars in these securitizations issued. Plus how many hundred of billions of second-lien loans? And can we forget CDOs? And CDOs squared?
And let's not forget all those completely synthetic CDOs that were written at the height of the mania. Most of it AAA, of course. Frankly, anyone stupid enough to buy a synthetic CDO should lose their money, but that is not what the courts will base their decision on. It is all about representations and warranties. And maybe a little fraud.
I picked on BAC because that is the analysis I saw. But it could be any of dozens of banks. Look at this list from the Branch Hill PowerPoint.

Could we see a hundred billion in losses to the major banks? In my opinion we will for sure, over time. $200 billion? Probably. $300 billion? Maybe. $400 billion? It depends on how organized the investors in the securities get and what gets settled out of court. Out of a few trillion dollars in securitizations? It's anybody's guess. I just made mine.
But let's not forget the $227 billion sold to Fannie and Freddie. Taxpayers are on the hook for $300-400 billion in losses. Those putbacks could save us a lot. Will this threaten the viability of some banks? Maybe. But most will survive. BAC made $3 billion last quarter. A steep yield curve (with the help of the Fed) can cure a lot of evils. But it will absorb the profits of a lot of banks for a long time.
And that of course, will come back to haunt the rest of us as banks have to raise more capital and get more conservative.
Anyone who owns stocks in banks with relatively large MBS exposure is not investing, they are gambling that the losses will not be more than management is telling them. There will be no bailouts (at least I hope not) this time around. Fool me once, shame on you; fool me twice, shame on me. There will be little sympathy for shareholders or bondholders this time, if it comes to that.
One more sad point. The FDIC (read taxpayers) is liable for some of this, as they took over some of these institutions. It just keeps on coming.
Final rant. If you were part of a group that knowingly created or sold flawed and fraudulent mortgage-backed securities to pensions and insurance companies and took home tens of millions in bonuses, up and down the management chain, maybe you should consider moving yourself and your money to a country that does not honor US extradition, because my guess is that, as all this comes out, you may have to hire some very expensive lawyers and get measured for pinstripes.
And the Mozilo agreement was a sham. Sigh. That would be the equivalent of fining me $10,000 and letting me keep my tanning bed. I don't have the space to go into the fraud at Countrywide, but their internal documents show they all knew what was going on.
Here Comes Mortgage Meltdown, Act 2 (part 1)
by John Mauldin:
Trouble, oh we got trouble, Right here in River City!
With a capital "T" That rhymes with "P"
And that stands for Pool, That stands for pool.
We've surely got trouble!
Right here in River City,
Right here! Gotta figger out a way
To keep the young ones moral after school!
Trouble, trouble, trouble, trouble, trouble...
- From The Music Man
(Quick last-minute note: I think this (and next week's) is/will be one of the more important letters I have written in the last ten years. Take the time to read, and if you agree send it on to friends and responsible parties. And note to new readers: this letter goes to 1.5 million of my closest friends. It is free. You can go to www.frontlinethoughts.com to subscribe. Now, let's jump in!)
There's trouble, my friends, and it is does indeed involve pool(s), but not in the pool hall. The real monster is hidden in those pools of subprime debt that have not gone away. When I first began writing and speaking about the coming subprime disaster, it was in late 2007 and early 2008. The subject was being dismissed in most polite circles. "The subprime problem," testified Ben Bernanke, "will be contained."
My early take? It would be a disaster for investors. I admit I did not see in January that it would bring down Lehman and trigger the worst banking crisis in 80 years, less than 18 months later. But it was clear that it would not be "contained." We had no idea.
I also said that it was going to create a monster legal battle down the road that would take years to develop. Well, in the fullness of time, those years have come nigh upon us. Today we briefly look at the housing market, then the mortgage foreclosure debacle, and then we go into the real problem lurking in the background. It is The Subprime Debacle, Act 2. It is NOT the mortgage foreclosure issue, as serious as that is. I seriously doubt it will be contained, as well. Could the confluence of a bank credit crisis in the US and a sovereign debt banking crisis in Europe lead to another full-blown world banking crisis? The potential is there. This situation wants some serious attention.
This letter is going to print a little longer. But I think it is important that you get a handle on this issue.
First, existing and new single-family home sales continue to slide, in the wake of the tax rebate that ended earlier this year. We have declined back to the down-sloping trend line. If you are a seller, this is not a pretty picture.

The homebuilding industry, which was the source of so many jobs last decade (aka the good old days), is on its back. This country needs a healthy housing construction market to get back to lower unemployment, and until the overhang in the foreclosure market is cleared out, that is unlikely to happen.

Lending is tighter, as is reasonable. Banks actually expect you to have the ability to pay back the mortgage you take out (solid FICO scores) and want reasonable down payments. Only 47% of applicants have the FICO score to get the best mortgage rates.
(Sidebar: Gary writes, "Furthermore, false appraisals rose 50% in 2009 from 2008. The tax credit for first-time homebuyers cost taxpayers about $15 billion, twice the official forecast, in part due to fraud. Over 19,000 tax filers claimed the credit but didn't buy houses, while 74,000 who claimed $500 million in refunds already owned homes." Where are the regulators?)
Shilling thinks prices are likely to fall another 20%. Given what I am writing about in the next section, that is a possibility. There is certainly no demand pressure to push up housing prices.
Finally, two charts on foreclosures. Residential mortgages in foreclosure are near all-time highs, close to 1 in 21 of all mortgages, up from 1 in 100 just four years ago. That's got to be bad for your profit models.


Anyone who tells you the housing problem is "bottoming" either has an agenda or simply does not pay attention to the data. I really want to see housing bottom and then turn around and the home builders come back; the nation desperately needs the jobs. But my job is to be realistic. When we see 3-4 months of non-stimulus-induced housing sales growth, then we can start talking about bottoms.
But housing sales are not really the issue. Let's look at the next leg of the problem.
"Dear Readers, this text came to me in an email from sources that are in the financial services business and with whom I have a personal relationship. The original text was laced with expletives and I would not use it in the form I received it. Therefore the text below has had some substantial editing in order to remove that language. The intentions of the writer are undisturbed. The writer shall remain anonymous. This text echoes some of the news items we have seen and heard today; however, it can serve as a plain language description of the present foreclosure-suspension mess. There is a lot here. It takes about ten minutes to read it. - David Kotok (www.cumber.com)
"Homeowners can only be foreclosed and evicted from their homes by the person or institution who actually has the loan paper...only the note-holder has legal standing to ask a court to foreclose and evict. Not the mortgage, the note, which is the actual IOU that people sign, promising to pay back the mortgage loan
"Before mortgage-backed securities, most mortgage loans were issued by the local savings & loan. So the note usually didn't go anywhere: it stayed in the offices of the S&L down the street.
"But once mortgage loan securitization happened, things got sloppy...they got sloppy by the very nature of mortgage-backed securities.
"The whole purpose of MBSs was for different investors to have their different risk appetites satiated with different bonds. Some bond customers wanted super-safe bonds with low returns, some others wanted riskier bonds with correspondingly higher rates of return.
"Therefore, as everyone knows, the loans were 'bundled' into REMICs (Real-Estate Mortgage Investment Conduits, a special vehicle designed to hold the loans for tax purposes), and then "sliced & diced"...split up and put into tranches, according to their likelihood of default, their interest rates, and other characteristics.
"This slicing and dicing created 'senior tranches,' where the loans would likely be paid in full, if the past history of mortgage loan statistics was to be believed. And it also created 'junior tranches,' where the loans might well default, again according to past history and statistics. (A whole range of tranches was created, of course, but for the purposes of this discussion we can ignore all those countless other variations.)
"These various tranches were sold to different investors, according to their risk appetite. That's why some of the MBS bonds were rated as safe as Treasury bonds, and others were rated by the ratings agencies as risky as junk bonds.
"But here's the key issue: When an MBS was first created, all the mortgages were pristine...none had defaulted yet, because they were all brand-new loans. Statistically, some would default and some others would be paid back in full...but which ones specifically would default? No one knew, of course. If I toss a coin 1,000 times, statistically, 500 tosses the coin will land heads...but what will the result be of, say, the 723rd toss? No one knows.
"Same with mortgages.
"So in fact, it wasn't that the riskier loans were in junior tranches and the safer ones were in senior tranches: rather, all the loans were in the REMIC, and if and when a mortgage in a given bundle of mortgages defaulted, the junior tranche holders would take the losses first, and the senior tranche holder last.
"But who were the owners of the junior-tranche bond and the senior-tranche bonds? Two different people. Therefore, the mortgage note was not actually signed over to the bond holder. In fact, it couldn't be signed over. Because, again, since no one knew which mortgage would default first, it was impossible to assign a specific mortgage to a specific bond.
"Therefore, how to make sure the safe mortgage loan stayed with the safe MBS tranche, and the risky and/or defaulting mortgage went to the riskier tranche?
"Enter stage right the famed MERS...the Mortgage Electronic Registration System.
"MERS was the repository of these digitized mortgage notes that the banks originated from the actual mortgage loans signed by homebuyers. MERS was jointly owned by Fannie Mae and Freddie Mac (yes, those two again ...I know, I know: like the chlamydia and the gonorrhea of the financial world...you cure 'em, but they just keep coming back).
"The purpose of MERS was to help in the securitization process. Basically, MERS directed defaulting mortgages to the appropriate tranches of mortgage bonds. MERS was essentially where the digitized mortgage notes were sliced and diced and rearranged so as to create the mortgage-backed securities. Think of MERS as Dr. Frankenstein's operating table, where the beast got put together.
"However, legally...and this is the important part...MERS didn't hold any mortgage notes: the true owner of the mortgage notes should have been the REMICs.
"But the REMICs didn't own the notes either, because of a fluke of the ratings agencies: the REMICs had to be "bankruptcy remote," in order to get the precious ratings needed to peddle mortgage-backed Securities to institutional investors.
"So somewhere between the REMICs and MERS, the chain of title was broken.
"Now, what does 'broken chain of title' mean? Simple: when a homebuyer signs a mortgage, the key document is the note. As I said before, it's the actual IOU. In order for the mortgage note to be sold or transferred to someone else (and therefore turned into a mortgage-backed security), this document has to be physically endorsed to the next person. All of these signatures on the note are called the 'chain of title.'
"You can endorse the note as many times as you please...but you have to have a clear chain of title right on the actual note: I sold the note to Moe, who sold it to Larry, who sold it to Curly, and all our notarized signatures are actually, physically, on the note, one after the other.
"If for whatever reason any of these signatures is skipped, then the chain of title is said to be broken. Therefore, legally, the mortgage note is no longer valid. That is, the person who took out the mortgage loan to pay for the house no longer owes the loan, because he no longer knows whom to pay.
"To repeat: if the chain of title of the note is broken, then the borrower no longer owes any money on the loan.
"Read that last sentence again, please. Don't worry, I'll wait.
"You read it again? Good: Now you see the can of worms that's opening up.
"The broken chain of title might not have been an issue if there hadn't been an unusual number of foreclosures. Before the housing bubble collapse, the people who defaulted on their mortgages wouldn't have bothered to check to see that the paperwork was in order.
"But as everyone knows, following the housing collapse of 2007-'10-and-counting, there has been a boatload of foreclosures...and foreclosures on a lot of people who weren't sloppy bums who skipped out on their mortgage payments, but smart and cautious people who got squeezed by circumstances.
"These people started contesting their foreclosures and evictions, and so started looking into the chain-of-title issue, and that's when the paperwork became important. So the chain of title became crucial and the botched paperwork became a nontrivial issue.
"Now, the banks had hired 'foreclosure mills'...law firms that specialized in foreclosures...in order to handle the massive volume of foreclosures and evictions that occurred because of the housing crisis. The foreclosure mills, as one would expect, were the first to spot the broken chain of titles.
"Well, what do you know, it turns out that these foreclosure mills might have faked and falsified documentation, so as to fraudulently repair the chain-of-title issue, thereby 'proving' that the banks had judicial standing to foreclose on delinquent mortgages. These foreclosure mills might have even forged the loan note itself...
"Wait, why am I hedging? The foreclosure mills did actually, deliberately, and categorically fake and falsify documents, in order to expedite these foreclosures and evictions. Yves Smith at Naked Capitalism, who has been all over this story, put up a price list for this 'service' from a company called DocX...yes, a price list for forged documents. Talk about your one-stop shopping!
"So in other words, a massive fraud was carried out, with the inevitable innocent bystanders getting caught up in the fraud: the guy who got foreclosed and evicted from his home in Florida, even though he didn't actually have a mortgage, and in fact owned his house free - and clear. The family that was foreclosed and evicted, even though they had a perfect mortgage payment record. Et cetera, depressing et cetera.
"Now, the reason this all came to light is not because too many people were getting screwed by the banks or the government or someone with some power saw what was going on and decided to put a stop to it...that would have been nice, to see a shining knight in armor, riding on a white horse.
"But that's not how America works nowadays.
"No, alarm bells started going off when the title insurance companies started to refuse to insure the titles.
"In every sale, a title insurance company insures that the title is free -and clear ...that the prospective buyer is in fact buying a properly vetted house, with its title issues all in order. Title insurance companies stopped providing their service because...of course...they didn't want to expose themselves to the risk that the chain of title had been broken, and that the bank had illegally foreclosed on the previous owner.
"That's when things started getting interesting: that's when the attorneys general of various states started snooping around and making noises (elections are coming up, after all).
"The fact that Ally Financial (formerly GMAC), JP Morgan Chase, and now Bank of America have suspended foreclosures signals that this is a serious problem...obviously. Banks that size, with that much exposure to foreclosed properties, don't suspend foreclosures just because they're good corporate citizens who want to do the right thing, and who have all their paperwork in strict order...they're halting their foreclosures for a reason.
"The move by the United States Congress last week, to sneak by the Interstate Recognition of Notarizations Act? That was all the banking lobby. They wanted to shove down that law, so that their foreclosure mills' forged and fraudulent documents would not be scrutinized by out-of-state judges. (The spineless cowards in the Senate carried out their master's will by a voice vote...so that there would be no registry of who had voted for it, and therefore no accountability.)
"And President Obama's pocket veto of the measure? He had to veto it...if he'd signed it, there would have been political hell to pay, plus it would have been challenged almost immediately, and likely overturned as unconstitutional in short order. (But he didn't have the gumption to come right out and veto it...he pocket vetoed it.)
"As soon as the White House announced the pocket veto...the very next day!...Bank of America halted all foreclosures, nationwide.
"Why do you think that happened? Because the banks are in trouble...again. Over the same thing as last time...the damned mortgage-backed securities!
"The reason the banks are in the tank again is, if they've been foreclosing on people they didn't have the legal right to foreclose on, then those people have the right to get their houses back. And the people who bought those foreclosed houses from the bank might not actually own the houses they paid for.
"And it won't matter if a particular case...or even most cases...were on the up -and up: It won't matter if most of the foreclosures and evictions were truly due to the homeowner failing to pay his mortgage. The fraud committed by the foreclosure mills casts enough doubt that, now, all foreclosures come into question. Not only that, all mortgages come into question.
"People still haven't figured out what all this means. But I'll tell you: if enough mortgage-paying homeowners realize that they may be able to get out of their mortgage loans and keep their houses, scott-free? That's basically a license to halt payments right now, thank you. That's basically a license to tell the banks to take a hike.
"What are the banks going to do...try to foreclose and then evict you? Show me the paper, Mr. Banker, will be all you need to say.
"This is a major, major crisis. The Lehman bankruptcy could be a spring rain compared to this hurricane. And if this isn't handled right...and handled right quick, in the next couple of weeks at the outside...this crisis could also spell the end of the mortgage business altogether. Of banking altogether. Hell, of civil society. What do you think happens in a country when the citizens realize they don't need to pay their debts?"
(I am not sure who wrote this, but if you want your 15 minutes of fame, I will be glad to credit you next week. - John)
Someone borrowed money for a mortgage. Some entity is cashing a check if that person is paying. That entity should have the title until it is paid off. If someone is not making their mortgage payments, they should be removed from the house and it should be sold to the benefit of the ultimately correct and what everyone thought was the proper title holder.
If you took out a mortgage and now the title is in some doubt because the investment banks and mortgage banks and all the middle guys screwed up (big-time!) because they wanted to save some bucks and make some commissions, you did not win the lottery. That is not America as I know it. You can't pay the mortgage, I am sorry. But you do not get to keep the house. The people who (thought) they bought the mortgage in a fair deal need to end up with that mortgage.
If you pay your mortgage, you get to have the American Dream.
We CANNOT allow this debacle to continue. It will bring the system down. Who will want to buy a mortgage that is in a securitized package with no clear title? Who will get title insurance? Some judge somewhere is going to make a ruling that is going to petrify every title company, and the whole thing grinds to a halt.
Let's be very clear. If we cannot securitize mortgages, there is no mortgage market. We cannot go back to where lenders warehoused the notes. It would take a decade to build that infrastructure. In the meantime, housing prices are devastated. Whatever wealth effect remains from housing gets worse, and the economy rolls over.
This is beyond my pay grade, but there have to be some adults who can make everyone play nice in the sandbox. Ideally, someone in authority at the Treasury, with bipartisan support steps in and says everyone follow these rules, whatever these rules need to be.
I had a very spirited conversation with good friend Barry Ritholtz today (of The Big Picture). Barry runs money but is also a lawyer and has a somewhat different perspective. He thinks we do not need any legislation and there is a legal cure. He says that real trained people (lawyers and paralegals) need to look at each mortgage and figure it out, and that it can get resolved. It is expensive to the banks; but I agree, if it is just dollars I don't care. Fix it.
But that is a maybe. Other people I talk to disagree. Some think we need some regulatory fixes. Some think we will need a legislative cure. But if we need to, there need be no finger pointing, no partisan BS. This needs to get solved.
Someone took out a mortgage. Some entity thinks they are owed money. Fix the damn paper trail so that happens, whether in a legal if time-consuming manner, in a regulatory fix, or with legislation.
Now, that is not to say the people who did this stuff did not commit felonies and such. We can sort that out over time. The longer we wait the worse it will get. Fix the problem and then go round up the bad guys. There are bigger issues in play here. (I know this will be somewhat controversial. Oh well.)
I get the fraud being done here. I am regulated by FINRA, the NFA, various states, the British FSA, and ultimately the SEC. If I did something in my business like the stuff described above, someone would come in and justifiably shut me down, fine me, and ban me from the securities business. Oh, wait. These guys ARE regulated by the above groups.
Finally on this topic, I shake my head when I think that the FDIC is now running several of the banks (think IndyMac) that are part of this foreclosure crisis. These are the guys who are supposed to be preventing something like this. Again, where are the adults?
All those subprime and Alt-A mortgages written in the middle of the last decade? They were packaged and sold in securities. They have had huge losses. But those securities had representations and warranties about what was in them. And guess what, the investment banks may have stretched credibility about those warranties. There is the real probability that the investment banks that sold them are going to have to buy them back. We are talking the potential for multiple hundreds of billions of dollars in losses that will have to be eaten by the large investment banks. We will get into details, but it could create the potential for some banks to have real problems.
And all this coming as European banks are going to have to sort out their own sovereign debt problems. Shades of 2008. I hope I am wrong, but it's all connected.
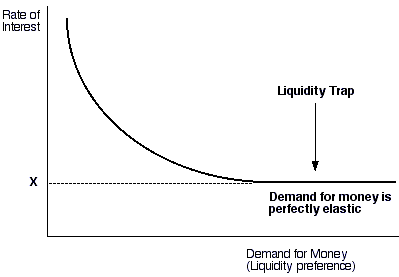
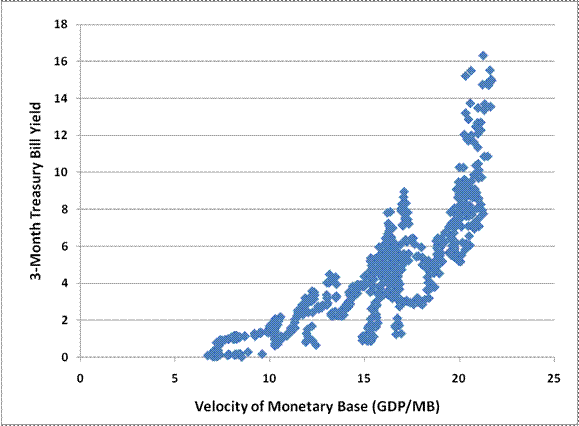
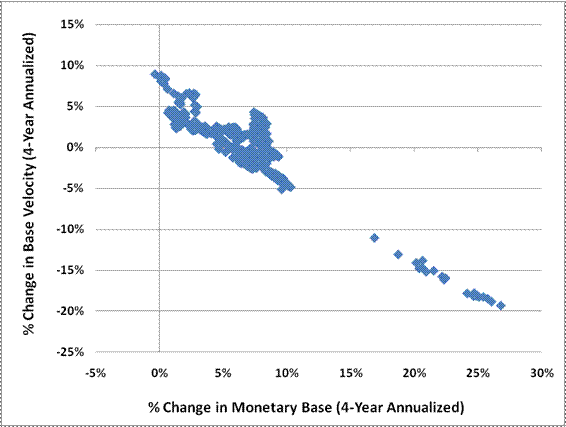
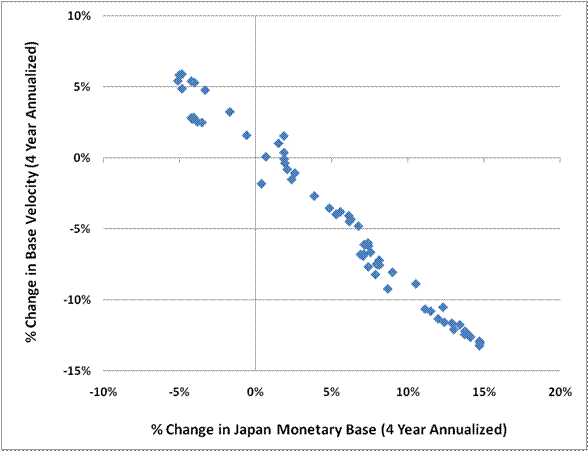
John Hussman: We Are In a Classic Liquidity Trap
It's a Dollar Debacle!


Sunday, October 24, 2010
Home Prices Begin Double Dip
CNBC reported that home prices slipped 6% in the past two months.
It gets worse: Gary Shilling is predicting an additional 20% drop in housing prices. That means that homeowner mortgages that are underwater will nearly double from 23% to 40%! More housing misery to come!
Fitch Downgrades U.S. Banks' Debt
"Today, Fitch Ratings issued a number of separate press releases placing on Rating Watch Negative most U.S. bank and bank holding companies' Support Ratings, Support Floors and other ratings that are sovereign-support dependent. The two companies mostly impacted by this announcement are Bank of America Corporation and Citigroup, Inc."